

Top Mobile Companies in San Francisco Bay Area, CA (268)
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.

Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a mid-20s pace, with Q2 FY2027 up 26.2% year over year and FY2026 up 24.4%. Guidance was raised to approximately $910–$913 million, reinforcing near-term momentum.
Customer Loyalty & Retention: Net revenue retention is 110%, indicating existing customers expand spending overall. Enterprise adoption is deepening, with 361 customers at $500K+ ARR, up from 282 a year earlier.
Healthy Cash Flow: Free cash flow and operating cash flow improved meaningfully, including Q2 FY2027 free cash flow of $21.7 million versus $3.5 million a year earlier. Adjusted operating income also rose to $22.0 million in the quarter.

Doximity is the leading clinical AI company with the largest network of U.S. clinicians. Doximity’s AI-powered workflow platform is trusted by over 85% of U.S. physicians and 300+ health systems. Doximity's mission is to help clinicians be more productive so they can provide better care for their patients. We are physicians-first, putting technology to work for doctors instead of the...

Doximity's Top Stability & Growth Strengths
Healthy Cash Flow: Free cash flow reached $317.5M in FY2026, up 19% year over year, underscoring strong cash generation. Operating cash flow also increased 19% to $326.5M, indicating robust cash conversion.
Profitability: Operating profitability expanded in FY2026, with adjusted EBITDA rising 14% to $357.8M. This points to solid earnings power alongside multi‑year revenue growth.
Strong Market Position & Advantage: Platform reach includes more than 85% of U.S. physicians, and workflow‑active prescribers grew 30%+ year over year. AI Search queries also rose more than 25% quarter over quarter, evidencing deepening engagement.
SoFi wasn’t built to be a bank. Or a technology company. We were built for one mission: help people achieve financial independence so they can realize their ambitions. Redefining an entire industry isn’t easy work—and it’s not for the faint of heart. It takes a certain kind of team. People with diverse perspectives and expertise, united by a common sense of...
SoFi's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating, with Q2 2026 GAAP net revenue up 43% year over year to about $1.219 billion and multi-year increases from 2023–2025; management also raised 2026 adjusted revenue guidance to $4.75–$4.85 billion.
Profitability: GAAP net income rose 61% year over year in Q2 2026 to $156.6 million. Adjusted EBITDA reached a record $357.8 million, up 44%.
Diversified Revenue Streams: Fee-based revenue increased to roughly $472 million in Q2 2026 and Financial Services revenue grew 29% year over year, helping reduce reliance on interest income from loans. Cross-buying is rising, with 51% of new products opened by existing members.

Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 35% year over year in Q2 2026 to roughly $219–$220 million, marking the eleventh consecutive quarter of growth. Management also guided full-year 2026 revenue to $870–$880 million, extending momentum after approximately 32% growth in 2025.
Healthy Cash Flow: Trailing twelve‑month operating cash flow increased about 90% to $237 million and free cash flow rose 142% to $184 million as of Q2 2026. These gains indicate that expanding revenue is converting into stronger cash generation.
Investor Backing & Capital Strength: The company completed a Nasdaq IPO in 2026 and previously secured a minority investment from General Atlantic at a multi‑billion‑dollar valuation. These milestones suggest strengthened access to capital alongside continued scaling of its advertising platform.
At Affirm, we help people say yes to the things that matter with flexible, transparent ways to pay over time. No hidden fees, no compound interest, and no fine print—just a smarter way to spend.

Affirm's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising sharply, reaching approximately $4.26–$4.3 billion in FY2026 with about 32% year-over-year growth, alongside multiple quarters of 30%+ revenue increases. GMV also expanded to roughly $50.2 billion, indicating broad-based top-line momentum.
Profitability: Profitability is improving, as operating results shifted from a loss of about $616 million in FY2024 and $87 million in FY2025 to approximately $417 million in operating income in FY2026. Recent quarters also reported positive GAAP operating income and stronger margins.
Product Line Growth: Newer products are scaling quickly, with Affirm Card GMV up roughly 146%–159% year over year and active cardholders more than doubling across recent quarters. Increasing transactions per active consumer and broader merchant adoption reinforce expansion across both core BNPL and card-driven use cases.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
TIDAL is a global music streaming platform bringing fans closer to artists through unique experiences and the highest sound quality. Artists and musicians are inherently entrepreneurial. They face a lot of the same challenges Square constantly works to solve for small business owners. The intersection between artists and the economy is getting increasingly more frequent (examples: merch stores, NFTs, and...
TIDAL's Top Stability & Growth Strengths
Product Line Growth: Product development and artist tools have expanded, including Hi‑Res FLAC, Dolby Atmos, DJ features, artist uploads, and direct‑to‑fan commerce with a 0% platform fee for US artists. These moves broaden the offering and signal ongoing product momentum even if subscriber growth is unverified.
Diversified Revenue Streams: Subscriptions are being supplemented by direct sales of music and merchandise to fans, and pricing updates aim to lift revenue per subscriber. This mix introduces additional monetization paths beyond the core streaming plan.
Strategic Partnerships: The platform remains available in more than 60 countries with integrations across audio, DJ, and automotive ecosystems, and maintains relationships with hundreds of labels and distributors. Such ties support distribution and content availability that can underpin commercial opportunities.
.png)
We bring people together around the things they love and turn their passions into their livelihood.

Whatnot's Top Stability & Growth Strengths
Strong Revenue Growth: Marketplace sales are described as surpassing $8B in 2025 and more than doubling from 2024, with first-half 2026 reportedly already exceeding all of 2025. Independent estimates also point to revenue scaling toward $1B in 2025, reinforcing commercial momentum.
Investor Backing & Capital Strength: Funding includes a $545M Series G at a reported $20B valuation, a substantial step up from the prior round. This signals deep capital access to fuel expansion and operations.
Market Expansion: Operations and hiring span hubs across the U.S. and Europe, while the platform added dozens of new categories and crossed one billion orders. These moves indicate broadening geographic reach and category depth.
Headquartered in New York City, Take-Two Interactive Software, Inc. is a leading developer, publisher, and marketer of interactive entertainment for consumers around the globe. We develop and publish products principally through Rockstar Games, 2K, and Zynga. Our strategy is to create hit entertainment experiences, delivered on every platform relevant to our audience through a variety of sound business models. Our...
Take-Two Interactive Software's Top Stability & Growth Strengths
Strong Revenue Growth: Annual revenue and net bookings rose materially in FY2026, and guidance points to a further step-up in FY2027. The company highlights a sizable year-over-year increase in revenue and a higher bookings outlook tied to its pipeline.
Diversified Revenue Streams: Recurring consumer spending makes up a large share of results and mobile contributes meaningfully alongside console and PC franchises. This mix across Rockstar, 2K, and Zynga supports ongoing monetization between major releases.
Future-Ready Strategy: A defined pipeline anchored by the scheduled Grand Theft Auto VI launch and reaffirmed FY2027 bookings guidance signals preparation for the next growth phase. Management’s outlook ties expected expansion to both the new release and continued performance from sports and mobile titles.

2K is headquartered in Novato, California and is a wholly owned label of Take-Two Interactive Software, Inc. (NASDAQ: TTWO). Founded in 2005, 2K Games is a global video game company, publishing titles developed by some of the most influential game development studios in the world. Our studios responsible for developing 2K’s portfolio of world-class games across multiple platforms, include Visual...
2K's Top Stability & Growth Strengths
Strong Revenue Growth: Parent-company revenue and net bookings increased in fiscal 2026, with NBA 2K identified among the largest contributors, and franchise revenue for NBA 2K rising materially year over year. NBA 2K26 unit sell-in also exceeded the prior title’s level, reinforcing momentum.
Product Line Growth: Multiple 2K releases were cited among leading contributors, including NBA 2K26 and WWE 2K26, while the active slate spans Civilization VII, Borderlands 4, and Mafia: The Old Country. This breadth indicates continued investment across several established franchises.
Customer Loyalty & Retention: Player engagement and recurrent consumer spending for NBA 2K increased meaningfully during fiscal 2026. Reported gains in daily active users alongside higher in-game spending point to durable participation within the ecosystem.
For over a decade, we built the infrastructure behind conversations, chat, voice, video, messaging APIs. We became the #1 CPaaS platform for in-app communications. 4,000+ brands trust us. 7 billion messages flow through our platform every month. 300 million monthly active users. We powered conversations for DoorDash, Match Group, Noom, Yahoo Sports, Rakuten, and thousands of others. We were good at...

Sendbird's Top Stability & Growth Strengths
Strong Market Position & Advantage: Feedback suggests Sendbird maintains substantial platform usage with billions of monthly conversations and hundreds of millions of active users, indicating entrenched positioning in in-app communications. Continued adoption by recognizable enterprises and presence across thousands of applications reinforce its competitive footing.
Innovation-Driven Growth: Feedback suggests the company is expanding its product scope into AI agents, voice AI, and related capabilities, signaling a push into higher-value customer-service automation beyond core chat APIs.
Strategic Partnerships: Feedback suggests the multi-year collaboration with AWS, integration with Amazon Bedrock, and marketplace distribution aim to extend reach and accelerate AI-focused go-to-market activity.
Initially built to take the pain out of peer-to-peer payments, Cash App has gone from a simple product with a single purpose to a dynamic app, bringing a better way to send, spend, invest, borrow and save to our millions of monthly active users. With a mission to redefine the world's relationship with money by making it more relatable, instantly...

Cash App's Top Stability & Growth Strengths
Profitability: Gross profit is rising strongly year over year, indicating expanding earnings power in the Cash App segment. This momentum is paired with gains across card spending, banking, and lending.
Diversified Revenue Streams: Expansion beyond peer-to-peer into banking, investing, lending, card, buy-now-pay-later, and commerce provides multiple monetization levers. Growth in primary banking activity and lending originations suggests broader product contribution to results.
Cost & Operational Efficiency: Operating discipline and AI-enabled processes are enabling more output with a smaller workforce. Financial performance improving alongside restructuring points to efficiency gains rather than scale-driven headcount growth.
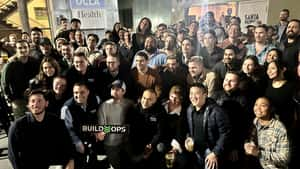
BuildOps is the AI-native platform for commercial contractors. Built for the complexity of large-scale commercial work, it replaces disconnected tools and manual workflows with a single system that runs every job from quote to close. At the center of the platform is OpsAI, BuildOps' intelligence layer designed for real work in the trades. OpsAI helps dispatchers send the right tech in...
BuildOps's Top Stability & Growth Strengths
Strong Revenue Growth: Reported three-year revenue growth of 1,012% and an Inc. 5000 rank of No. 336 indicate rapid scaling, and revenue was said to have doubled in both 2023 and 2024. Together these signals point to sustained top-line momentum.
Investor Backing & Capital Strength: A $127 million Series C at a reported $1 billion valuation and total funding exceeding $250 million signal substantial capital availability. This backing supports continued product development and go-to-market investment.
Market Expansion: New hubs in Raleigh and Toronto, government-confirmed plans for roughly 291 Raleigh jobs, and rising third‑party headcount estimates point to active geographic and organizational growth. Expanding offices and staffing suggest deeper North American coverage.

UserWise Services builds high-performance external teams for game studios, focusing on new game development, LiveOps, and growth using a proprietary AI-powered toolset.
Kiip is the leading ad tech and data platform powering mobile advertising that people like. To date, Kiip has worked with more than 500 brands, including Coca-Cola, Kellogg’s, Procter & Gamble, Johnson & Johnson, and McDonald’s, and is integrated into more than 7,000 mobile apps. Founded in 2010, Kiip has raised more than $32 million in venture cap
Samsung Electronics is a global technology company developing consumer electronics, mobile devices, and next-generation device solutions. Its mission is to explore technologies that help people worldwide lead happier, healthier lives. The company operates across consumer electronics, IT and mobile communications, and device solutions, offering products including Galaxy smartphones, tablets, watches, rings, televisions, computers, and audio equipment for customers around the...
Samsung's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests year-over-year increases in overall revenue, with specific quarters reporting mid-single-digit growth alongside positive operating profits.
Product Line Growth: Cloud computing, MSP, and AI Transformation (AX) offerings are expanding, with cloud revenue showing double-digit growth driven by SCP and GPUaaS demand.
Market Expansion: Digital logistics platforms such as Cello Square are scaling their user base and external business operations across international subsidiaries.

The Expeto solution offers Enterprise First integration of mobile networks and IIoT applications onto a single platform. By combining traditional telecommunication standards with our disruptive cloud and edge computing technology, the Expeto Nextworking platform provides an Enterprise First service framework that enables fast and secure control of mobile networks and applications. Through Expeto’s patent-pending platform as a service (PaaS) offer, we...

The GSMA is a global organisation unifying the mobile ecosystem to discover, develop and deliver innovation foundational to positive business environments and societal change. Our vision is to unlock the full power of connectivity so that people, industry and society thrive. We operate through three main pillars: Connectivity for Good engages members, governments and civil society, to advance positive policy and...
The ShopSavvy team had no idea back in 2008 they would play a major role in disrupting the retail shopping industry, but that is just what they did when they launched ShopSavvy. Since then, ShopSavvy has grown into the world’s largest mobile shopping community with more than 40 million downloads. It is helping both retailers and consumers open new lines...

Based in Silicon Valley, IMVU (imm-view) is the world’s largest friend and fashion discovery platform, and a top 5 grossing app in the App Store, where millions of users customize their characters and explore over 40,000 destinations to connect with each other. Through chat and events, IMVU’s massive metaverse enables and empowers friendship and human connection. A community of hundreds...



