

Top E-commerce Companies in San Francisco Bay Area, CA (331)

Rokt is the global leader in ecommerce, unlocking real-time relevance in the moment that matters most, the Transaction Moment™. The Rokt Brain and Rokt Network power billions of transactions and connect hundreds of millions of customers, and are trusted to do this by the world’s leading companies including Live Nation, Fanatics, Macy’s, AMC Theatres, PayPal, Uber, Hulu, Albertsons, and HelloFresh....

Rokt's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as scaling to an $800–$900 million annualized run rate, with multi-year acceleration from earlier levels and recognition on external growth lists. Company milestones also reference decade-long high growth and large increases in transactions and users.
Investor Backing & Capital Strength: Valuation is reported at $3.5 billion following a sizeable secondary transaction, alongside extensive funding from major institutional backers. Capital access is further underscored by commitments to headquarters expansion and sustained R&D investment.
Strong Market Position & Advantage: Enterprise adoption is portrayed as broad, including more than half of the top 200 global ecommerce companies and partnerships with brands like Uber, Live Nation, and PayPal/Venmo. Industry mentions such as Gartner’s Market Guide and placements on fast-growing company lists reinforce visibility in its specialized category.
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
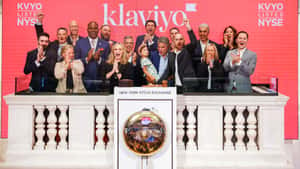
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has scaled to over $1.2B with continued double-digit quarterly increases and an outlook nearing $1.5B, indicating sustained momentum. Guidance increases reinforce the trajectory of ongoing top-line expansion.
Market Expansion: International revenue is growing faster than the overall business and now represents a significant share of total revenue, with customers across more than 100 countries. The customer base surpassing 205,000 underscores broader geographic reach and upmarket penetration.
Customer Loyalty & Retention: Net revenue retention remains above 100%, suggesting existing customers are expanding spend through cross-selling and wider platform adoption. Larger-account cohorts are growing rapidly, including rising counts of $50K+ and $1M+ ARR customers.
.jpg)
At Braze, we believe in the passion of our people. We seek to ignite that passion by setting high standards, championing teamwork, and creating work-life harmony. We thrive when people add their unique perspectives to our ever-growing teams—and we strive to empower you to make an impact that fuels both you, and our business.

Braze's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a mid-20s pace, with Q2 FY2027 up 26.2% year over year and FY2026 up 24.4%. Guidance was raised to approximately $910–$913 million, reinforcing near-term momentum.
Customer Loyalty & Retention: Net revenue retention is 110%, indicating existing customers expand spending overall. Enterprise adoption is deepening, with 361 customers at $500K+ ARR, up from 282 a year earlier.
Healthy Cash Flow: Free cash flow and operating cash flow improved meaningfully, including Q2 FY2027 free cash flow of $21.7 million versus $3.5 million a year earlier. Adjusted operating income also rose to $22.0 million in the quarter.
.png)
Expedia Group, Inc. is the global travel marketplace with one purpose: to help travelers explore the world, one journey at a time. Expedia Group™ connects travelers, partners, and advertisers through its trusted brands, leading technology, and rich first-party data, delivering predictive, personalized experiences that shape the future of travel. Expedia Group’s ecosystem includes three flagship consumer brands – Expedia®, Hotels.com®, and...

Expedia Group's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased 8% in 2025 and accelerated to 14% year over year in Q2 2026, with management raising full‑year revenue guidance to $16.05–$16.22 billion. Gross bookings also rose 8% in 2025 and 12% in Q2 2026, indicating expanding underlying travel activity.
Profitability: Operating income grew 42% in 2025 and surged 65% in Q2 2026, while GAAP net income jumped 166% in that quarter. Adjusted EBITDA rose 19% in 2025 and 23% in Q2 2026, suggesting improved operating leverage alongside growth.
Diversified Revenue Streams: Both distribution channels are contributing, with Q2 2026 B2B gross bookings up 21% (B2B revenue up 23%) and B2C gross bookings up 8%. Lodging remained a key driver as lodging gross bookings rose 11% and booked room nights increased 6% in Q2 2026.

Doximity is the leading clinical AI company with the largest network of U.S. clinicians. Doximity’s AI-powered workflow platform is trusted by over 85% of U.S. physicians and 300+ health systems. Doximity's mission is to help clinicians be more productive so they can provide better care for their patients. We are physicians-first, putting technology to work for doctors instead of the...

Doximity's Top Stability & Growth Strengths
Healthy Cash Flow: Free cash flow reached $317.5M in FY2026, up 19% year over year, underscoring strong cash generation. Operating cash flow also increased 19% to $326.5M, indicating robust cash conversion.
Profitability: Operating profitability expanded in FY2026, with adjusted EBITDA rising 14% to $357.8M. This points to solid earnings power alongside multi‑year revenue growth.
Strong Market Position & Advantage: Platform reach includes more than 85% of U.S. physicians, and workflow‑active prescribers grew 30%+ year over year. AI Search queries also rose more than 25% quarter over quarter, evidencing deepening engagement.
DoorDash is a technology and logistics company focused on local commerce. Founded in 2013, it operates a food-ordering service and has expanded to more than 40 countries. The company uses technology and logistics to shape the future of local commerce. Its core business combines food ordering with delivery-oriented logistics, enabling the service to operate across a broad international footprint while...
DoorDash's Top Stability & Growth Strengths
Strong Revenue Growth: Financial results indicate broad year-over-year increases in revenue, total orders, and marketplace order value in 2025 and again in Q2 2026. Feedback suggests this momentum remains solid even after adjusting for acquisition effects.
Market Expansion: International reach has grown through Wolt and Deliveroo, alongside a new technology center in India with substantial planned hiring. Ongoing recruitment across multiple regions and functions underscores a widening operational footprint.
Diversified Revenue Streams: The company is expanding beyond restaurant delivery into grocery, retail, alcohol, advertising, merchant software, and new delivery technologies. Company updates describe these categories scaling alongside the core marketplace.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.

As the trusted choice for digital agencies, SaaS platforms, and web professionals, Duda powers over 1 million websites worldwide. Our platform offers a comprehensive suite of tools that enable users to efficiently create pixel-perfect, feature-rich websites at scale.

Duda, Inc.'s Top Stability & Growth Strengths
Innovation-Driven Growth: Product development is expanding with AI-assisted site creation, automation, APIs, commerce enhancements, and booking tools; feedback suggests these additions are being actively adopted across the platform. These moves indicate a focus on deepening value for agencies and partners and support continued commercial expansion.
Market Expansion: Platform adoption is described as growing, with more than 22,000–23,000 organizations and over a million active websites reported, alongside millions of sites built historically. External technology trackers highlighting recent installations further support ongoing usage across markets.
Strategic Partnerships: Partnerships such as the 2026 Epos Now integration and relationships with providers like Thryv, Hibu, and IONOS extend reach into established customer ecosystems. This partner-led, white‑label distribution model provides additional channels for acquiring and retaining end users.
Zeta Global (NYSE: ZETA) is the AI Marketing Cloud that leverages advanced artificial intelligence (AI) and trillions of consumer signals to make it easier for marketers to acquire, grow, and retain customers more efficiently. Through the Zeta Marketing Platform (ZMP), our vision is to make sophisticated marketing simple by unifying identity, intelligence, and omnichannel activation into a single platform –...
Zeta Global's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding rapidly, with 30% full-year growth in 2025 and 44% year over year in Q2 2026, alongside raised 2026 revenue guidance of roughly 39–40%.
Healthy Cash Flow: Cash generation is strengthening, with free cash flow up 78% in 2025 and 73% in Q2 2026, and 2026 free-cash-flow guidance around $255 million.
Profitability: Profitability is improving, highlighted by positive GAAP net income in Q2 2026 and an adjusted EBITDA margin of about 20.7% with continued expansion.

.png)
We bring people together around the things they love and turn their passions into their livelihood.

Whatnot's Top Stability & Growth Strengths
Strong Revenue Growth: Marketplace sales are described as surpassing $8B in 2025 and more than doubling from 2024, with first-half 2026 reportedly already exceeding all of 2025. Independent estimates also point to revenue scaling toward $1B in 2025, reinforcing commercial momentum.
Investor Backing & Capital Strength: Funding includes a $545M Series G at a reported $20B valuation, a substantial step up from the prior round. This signals deep capital access to fuel expansion and operations.
Market Expansion: Operations and hiring span hubs across the U.S. and Europe, while the platform added dozens of new categories and crossed one billion orders. These moves indicate broadening geographic reach and category depth.

Taskrabbit is a marketplace platform that conveniently connects people with Taskers to handle everyday home to-do’s, such as furniture assembly, handy work, moving help, and much more. Acquired by IKEA Group - the world’s largest furniture retailer - in 2017 At Taskrabbit, we want to make your neighborhood a little more familiar. Whether it’s a handyman (or woman!), a housecleaner, moving...

Taskrabbit's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as having grown substantially over the past five years, based on leadership commentary. This indicates rising top-line momentum even without public quarterly disclosures.
Market Expansion: Geographic coverage was extended to a nationwide footprint in the United States alongside ongoing international operations. This broader reach expands the addressable market and supports scaling of core categories.
Strategic Partnerships: Deeper integration with a major retail partner enables customers to add assembly at checkout, boosting conversion through that channel. This embedded distribution appears to reinforce demand generation beyond the standalone app.
Babylist is the trusted platform for millions of growing families. For over a decade, Babylist has been the technology solution for expecting parents and the community that supports them, expanding from baby registry into a full-service platform that helps parents make decisions with confidence, stay connected, and build happy and healthy families. Every year Babylist helps over 9M people make...
Babylist's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising rapidly, surpassing $750 million in 2025 with 45% year-over-year growth, alongside expanding customer reach. The multi-year trend from roughly $400 million in 2023 to $750 million-plus in 2025 points to sustained expansion across the core business.
Profitability: Profitability is reported for eight consecutive years through 2025, with adjusted EBITDA margin improving by five percentage points in 2025. This indicates expansion has been achieved without relying on sustained operating losses.
Diversified Revenue Streams: Growth extends beyond the registry into healthcare, media, retail, and financial services, with Health up 64% and Media up 35% year over year in 2025. Physical showrooms and fulfillment investments further support multiple avenues for monetization.
Decorist is the leading online interior design service that provides professional decorating help – in your style and on your budget – for a low flat fee. Whether you're moving, renovating or just want a fresh new look, Decorist is the easy and affordable way to design the room you've always wanted. Decorist also does affordable office design-perfect for start-ups!
Accounts Payable (and Receivable, too) Made Easy! At Checkbook, we have built a way to send and receive Digital Checks instead of dealing with paper and postage, or expensive online transactions. Digital Checks offer a clear financial and operational advantage for businesses with instant delivery, and online deposit, at a fraction of the cost of other payment options. Just $1 per...

Beauty for All Industries (BFA) is home to the largest beauty subscription brands in the world: IPSY and BoxyCharm, as well as brand incubator, Madeby Collective. We are uniquely situated at the nexus of tech and beauty and are a digitally native company – born and raised online, during the rise of social media. We approach everything we do with a...

Branders.com is an online seller of customizable promotional items such as pens, hats and more, for marketing, sales and event planning.

InterPayments is not a gateway or processor. We are for mid- and enterprise-size merchants who are dissatisfied with high credit card fees. Our surcharging technology works like your sales tax engine - but for card fees. Compliantly recover fees within your existing payment process without changing payment providers. We contractually guarantee compliance with the 67 jurisdictions that govern surcharging. Alternative surcharging...
Symphony Commerce is the leading provider of Commerce as a Service, with the only cloud platform natively-built to orchestrate commerce across multi-channel storefronts, orders, inventory, and fulfillment orchestration. Built by the visionary and technical team behind Amazon’s ordering and fulfillment systems, Symphony frees brands from the burden of infrastructure management and provides the data and services they need to operate...
.png)
HelloFresh is on a mission to change the way people eat, forever! From our 2011 founding in Europe’s vibrant tech hub Berlin, we’re evolving from the world’s leading meal kit company to the world's leading food solutions group. We delivered 227 million meals and reached 6.94 million active customers around the world in Q3 2021. HelloFresh Group consists of six brands...

HelloFresh's Top Stability & Growth Strengths
Strong Market Position & Advantage: Evidence indicates HelloFresh is widely regarded as the global market leader in meal kits by revenue, scale, and multi‑country footprint, particularly across North America and Europe. Consolidation in the U.S. (e.g., Blue Apron’s sale) has further concentrated share among scaled players like HelloFresh.
Profitability: Company communications highlight a pivot to higher‑value customers, positive adjusted EBITDA in FY 2025, and positive free cash flow in early 2026, signaling disciplined margin focus. Management emphasizes profitability before volume, with ongoing execution and cash generation programs.
Diversified Revenue Streams: A multi‑brand portfolio spanning cook‑and‑eat and ready‑to‑eat (Factor) across roughly 18 countries broadens price points and meal formats. Non‑U.S. RTE showed double‑digit growth, and new capacity (e.g., a Factor Europe facility in Germany) supports the category.

We are a consulting firm that specializes in engineering and management. We have provided services for some of the largest tech companies in the San Francisco Bay Area. These services include mechanical, electrical, software design, data collection quality assurance, and testing of new hardware and software. We pride ourselves in being a small company, which is able to be extremely...



