

Top Cloud Companies in San Francisco Bay Area, CA (586)
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding at strong double‑digit rates across recent quarters and the latest fiscal year, with cloud revenue and ARR also rising. Investor materials and quarterly updates highlight consistent momentum rather than a one‑off spike.
Strong Market Position & Advantage: Independent analyst recognitions position the company as a Leader across multiple core categories, and it serves a very large, global customer base including much of the Fortune 500. This broad market presence supports pricing power, cross‑sell, and durable demand.
Innovation-Driven Growth: Cloud migrations and newly introduced AI capabilities are cited as meaningful tailwinds for adoption and expansion. Product enhancements and platform integrations are associated with larger enterprise deals and a growing backlog of committed revenue.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Product Line Growth: Expansion from core data observability into AI/agent observability, with launches such as Observability Agents (2025), Agent Observability (2025–2026), and support for Databricks Agent Bricks, broadens the platform’s scope. Additional capabilities like machine learning metric monitors and deep ecosystem integrations reinforce product breadth.
Market Expansion: Claims of 400+ enterprise customers, monitoring of 10M tables, and ongoing publication of new enterprise deployments (e.g., Roche, Nasdaq, JetBlue, M&T Bank) indicate widening adoption. Continued enterprise case studies and category presence suggest sustained commercial reach.
Strong Revenue Growth: The company reported 100% year-over-year revenue growth in 2023 and said it added hundreds of customers that year. Earlier communications also highlighted rapid revenue expansion leading into its later-stage financing.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: Feedback suggests GAAP operating income turned positive in FY2026 and profitability has continued across recent quarters, indicating stronger earnings discipline.
Healthy Cash Flow: Feedback suggests free cash flow reached roughly $100M+ in FY2026 and remained solid in subsequent quarters, signaling improved cash generation.
Cost & Operational Efficiency: Feedback suggests margin expansion and restructuring efforts have driven better operating efficiency even as top-line growth slowed.
From solo developers building their first app to large enterprise teams if it needs to be fast, reliable, and beautifully built, it runs on Vercel. Our platform powers millions of deployments a day. We started with a simple belief: the web should be fast for everyone, everywhere. That belief became Next.js. Then a platform. Then the infrastructure layer for the...
Vercel's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from roughly $100M in early 2024 to about $340M by early 2026, with continued momentum into 2026. This trajectory is reinforced by reports of substantial run‑rate increases alongside expanding platform usage.
Investor Backing & Capital Strength: A $300M Series F at a $9.3B valuation—reported as oversubscribed and a marked step‑up from 2024—signals strong access to capital. Co‑lead participation by Accel and GIC underscores depth of investor demand.
Innovation-Driven Growth: AI offerings such as v0 are portrayed as rapidly scaling, with millions of users and a significant share of deployments initiated by coding agents. Platform metrics like daily deployments and AI Gateway usage indicate innovation is driving adoption and workload growth.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show operating revenue rising at double‑digit rates across FY2025 and FY2026, with annualized recurring revenue increasing even faster. Growth is supported by both subscriber additions and higher average revenue per customer.
Healthy Cash Flow: Free cash flow increased year over year, indicating stronger cash generation alongside expansion. Reported figures highlight rising cash metrics even as the company scales investments.
Market Expansion: International revenue and subscribers continued to grow, with substantial gains outside Australia/New Zealand and ongoing progress in the U.S. aided by product and acquisition initiatives. Regional momentum in markets like the UK and North America underscores a widening footprint.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is presented as expanding substantially across fiscal 2026 and into fiscal 2027, with multiple consecutive quarters showing strong year-over-year increases. The momentum spans both total revenue and subscription metrics, indicating broad-based top-line expansion.
Healthy Cash Flow: Operating cash flow and free cash flow are described as improving markedly, moving from modest levels to solid positive generation. Recent results also point to expanding contribution margins, suggesting better unit economics as scale increases.
Customer Loyalty & Retention: Average subscription dollar-based net retention is noted as comfortably above the expansion threshold, implying existing customers are growing their spend. Growth in the cohort of customers generating at least $100K in subscription ARR reinforces durable land-and-expand dynamics.
Snyk, the leader in secure AI software development, empowers organizations to build fast and stay secure by unleashing developer productivity and reducing business risk. The company’s AI Trust Platform seamlessly integrates into developer and security workflows to accelerate secure software delivery in the AI Era. Snyk delivers trusted, actionable insights and automated remediation, enabling modern organizations to innovate without limits....
Snyk's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue and ARR continued to rise, with ARR surpassing $300M by 2025 and revenue increasing in 2024. Feedback suggests growth has moderated from earlier hypergrowth into a steadier, efficiency‑focused trajectory while the customer base expanded to 4,500+.
Product Line Growth: Snyk Code reached $100M in ARR and newer offerings such as DAST and AI‑focused products (e.g., Evo) showed strong momentum. These developments indicate the platform is extending beyond its original core into additional security categories.
Market Expansion: Enterprise adoption intensified, with that segment driving a large share of new additions and AI security opening fresh routes to demand. Customer counts grew materially from 2024 into 2025, signaling broader market reach.
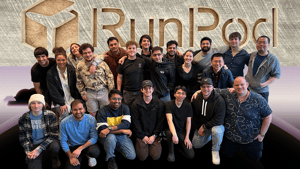
Runpod is pioneering the future of AI and machine learning, offering cutting-edge cloud infrastructure for full-stack AI applications. Founded in 2022, we are a rapidly growing, well-funded company with a remote-first organization spread globally. Our mission is to empower innovators and enterprises to unlock AI's true potential, driving technology and transforming industries. Join us as we shape the future of...
Runpod's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as scaling from about $120M ARR in January 2026 to roughly $240M annualized by June 2026, indicating rapid acceleration. This trajectory aligns with simultaneous expansion in developer adoption.
Investor Backing & Capital Strength: Capital raised includes a $100M Series A/growth round at a $1B valuation, alongside a prior $20M seed financing. These milestones signal substantial institutional support for continued scaling.
Customer Loyalty & Retention: Reported net dollar retention of 120% and 155% year-over-year signup growth indicate expanding spend among existing users alongside rapid acquisition. Developer counts moving from ~100K (2024) to 1M+ (2026) reinforce broadening platform engagement.
iManage is dedicated to Making Knowledge Work. Over one million professionals across 65+ countries rely on our intelligent, cloud-enabled, secure knowledge work platform to uncover & activate the knowledge that exists inside their business content and communications. We are continuously innovating to solve the most complex professional challenges & enable better business outcomes. Our work is not always easy but it...

iManage's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue is described as rising sharply over recent periods with continued uplift into the following year. These signals point to a scaling recurring-revenue model rather than one-off sales.
Market Expansion: Hundreds of new customer logos were added across successive years, with net customer growth and significant increases in cloud usage across regions such as Asia and ANZ. This reflects expansion beyond North America and deeper penetration within the installed base.
Innovation-Driven Growth: Rapid cloud migration and the rollout of AI capabilities (e.g., Ask iManage, AI Enrichment, Insight+) are portrayed as key adoption catalysts. These innovations appear to be driving multi-solution uptake and greater platform stickiness among enterprises.

Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.

Samsara (NYSE: IOT) is the pioneer of the Connected Operations® Platform, which is an open platform that connects the people, devices, and systems of some of the world’s most complex operations, allowing them to develop actionable insights and improve their operations. With tens of thousands of customers across North America and Europe, Samsara is a proud technology partner to the...

Samsara's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at around 30% year over year across recent quarters and fiscal periods, indicating continued expansion at scale. Growth is not primarily a currency effect and has been maintained across multiple updates.
Profitability: GAAP profitability has been achieved for multiple consecutive quarters, with operating income turning positive versus a loss a year earlier. Margin expansion and improved free cash flow underscore operating leverage.
Resilient & Sustainable Growth: Growth has been sustained at roughly the same pace across recent quarters and the prior fiscal year rather than spiking in a single period. Large-customer momentum and multi-product adoption underpin this consistency.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Observability revenues are described as rising sharply across consecutive years, with ThousandEyes repeatedly identified as a primary contributor to that momentum. Growth continued thereafter even as the broader category’s pace moderated, indicating durable contribution from ThousandEyes.
Market Expansion: ThousandEyes has been embedded into Cisco’s Digital Experience Assurance and extended across enterprise networks, the public Internet, SaaS, and public-cloud environments. Customer penetration among large enterprises has increased materially since FY2020, signaling broader reach and adoption.
Product Line Growth: Cisco has continued to add capabilities such as Cloud Insights and Traffic Insights while integrating data from Meraki and Catalyst. These enhancements expand use cases beyond standalone monitoring toward end‑to‑end network assurance.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising from $1.62B in FY2023 to $2.17B in FY2024, $2.67B in FY2025, and about $3.35B in FY2026, with Q4 FY2026 up 25% year over year. This trajectory, alongside mid‑20% ARR growth, indicates continued expansion rather than a stall.
Healthy Cash Flow: Cash generation is growing, with free cash flow rising to about $779M in FY2026 and a free‑cash‑flow margin near 23%. Non‑GAAP operating metrics, including an ~80% gross margin, underscore operating leverage.
Strong Market Position & Advantage: Industry evaluations list the company as a Leader in the 2026 Gartner Magic Quadrants for both SSE and SASE, with five consecutive years of SSE leadership. Expanding large‑enterprise adoption and thousands of customers support a durable position in its core zero trust/SSE markets.
Our mission is to remove inefficiency from the foundation of AI. By combining new research in information theory, probabilistic modeling, and distributed systems, we’re creating self-optimizing data infrastructure that continuously improves how information is represented and used by intelligent systems.

Granica's Top Stability & Growth Strengths
Product Line Growth: The platform has expanded from data reduction/privacy into Large Tabular Models and Myelin for stateful AI agents, signaling a broader offering. Company materials describe substantial production usage and named deployments, indicating movement beyond a single-product footprint.
Strategic Partnerships: The company joined the Google Cloud Partner Advantage program and lists availability/integrations across major ecosystems, including cloud marketplaces and a recorded Databricks partnership. These channels suggest deeper enterprise distribution with managed, hybrid, and self-managed deployment options.
Investor Backing & Capital Strength: A $45M Series A led by top-tier investors is documented, and the company now states it has raised more than $60M. This points to continued access to capital even though the most clearly documented major round remains the 2023 Series A.
Rundoo is the AI-native, all-in-one ERP for independent supply stores: point of sale, inventory, payments, and the general ledger in one system. We serve independent paint, hardware, and farm & feed retailers who've been stuck running their business on outdated point-of-sale systems and a patchwork of disconnected software, and we're built to help them modernize: better experiences for them, their...

Rundoo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor support is described as robust, with a $30M Series B led by Battery Ventures and participation from Bessemer and CRV, bringing total funding to $48M. This capital is earmarked to scale engineering and go-to-market operations.
Market Expansion: The company is said to serve 500+ independent stores across the U.S., Canada, and the Caribbean and plans to grow teams in Redwood City and Chicago. These moves indicate widening geographic reach and operational scale.
Innovation-Driven Growth: AI capabilities, including the “Dooey” agent, are highlighted as a leading reason customers choose the platform, with external coverage noting the growing importance of its AI functionality. Reported 5,000+ users on the customer app suggest expanding product adoption beyond store employees.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Profitability: Adjusted EBITA and margins improved markedly in 2025, with adjusted EBITA rising from SEK 27.2B to SEK 42.9B and margin from 11.0% to 18.1%. Margin resilience continued into 2026 despite mixed sales.
Resilient & Sustainable Growth: Underlying sales show modest improvement, with +6% organic growth in Q1 2026 and +2% for H1 2026. Organic growth also appeared in three of four market areas in Q2 2026.
Healthy Cash Flow: Cash generation remained positive, with H1 2026 free cash flow before M&A up year over year. Net cash strengthened versus the prior year, supporting financial flexibility.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate FY2026 revenue rose 19% year over year to roughly $2.02B, with Q1 FY2027 revenue up 16% and ARR up 17%. This points to steady double‑digit expansion across both total and recurring revenue.
Customer Loyalty & Retention: Dollar-based net retention is reported around 110–111%, and ARR growth has tracked slightly ahead of revenue growth. These signals suggest existing customers are expanding usage alongside new logo additions.
Healthy Cash Flow: Company materials highlight strong free cash flow alongside growth, including substantial FY2026 free cash flow and robust margins in recent quarters. The business has also returned capital via notable share repurchases.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is considered to be expanding rapidly, with recent quarters showing accelerated year-over-year gains in both total and subscription revenue. Multi-year growth at a high double-digit pace is also evident in the latest annual results.
Resilient & Sustainable Growth: Contracted revenue indicators appear robust, with total RPO at $29.0B and current RPO at $13.2B in Q2 2026. Management also raised its full-year 2026 subscription outlook, signaling confidence in continued expansion.
Innovation-Driven Growth: Newer AI offerings are gaining commercial traction, with ServiceNow AI surpassing $1 billion in annual contract value and agentic deployments scaling quickly. Large-deal activity and the count of very large customers also increased, indicating product-led expansion.
Biotechnology is rewriting life as we know it, from the medicines we take, to the crops we grow, and the household goods that we rely on every day. But moving at the new speed of science requires better technology. Benchling’s mission is to unlock the power of biotechnology. The world’s most innovative biotech companies use Benchling’s R&D Cloud to power the...
Benchling's Top Stability & Growth Strengths
Strong Market Position & Advantage: Adoption spans 1,300+ biotechnology organizations with usage reported across more than half of the top 50 biopharma companies, signaling durable positioning in life‑sciences R&D software. Multiple sources characterize the platform as a leading life‑sciences R&D cloud used by both startups and major enterprises.
Product Line Growth: The company continues to launch and expand major offerings, including Benchling AI, antibody‑discovery capabilities, automation/analysis tools, and extensions into new scientific workflows such as small‑molecule chemistry. Acquisitions like PipeBio further broaden capability depth in biologics and related R&D domains.
Innovation-Driven Growth: AI is a clear growth vector, with reports that 500 biotech companies used Benchling AI in its first year and the product subsequently reached general availability. Team acquisitions (e.g., ReSync Bio and Sphinx Bio) and partnerships (e.g., with Anthropic) underscore a deliberate push to embed advanced models into scientific workflows.



