

Top Machine Learning Companies in San Francisco Bay Area, CA (490)
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is increasing at a double‑digit pace, with Q2 2026 revenue of about $1.91B up year over year. Full-year 2025 revenue also rose meaningfully to roughly $6.15B from $4.96B the prior year, indicating momentum across periods.
Profitability: Profitability is improving, as Q2 2026 net income increased to about $154M and operating income to roughly $152M from the prior year’s quarter. Recurring gross profit from subscription and fintech reached approximately $585M, showing stronger unit economics alongside scale.
Market Expansion: Customer reach is widening, with roughly 9,500 net locations added in Q2 2026 and total locations around 180,000, both higher than a year earlier. The company is also extending into retail, enterprise, international markets, and AI-enabled products such as Toast IQ.
At Capital One, we think and work like a tech company, using our digital fluency to transform everything about the customer experience. We’re bending data to our will, and turning a stodgy industry on its head. That’s reflected in our ranking as the number one business technology innovator in the U.S. in the 2016 InformationWeek Elite 100.
Capital One's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate revenue increased year over year and sequentially, with quarterly revenue reaching roughly the mid‑teens in billions and full-year 2025 revenue rising markedly versus 2024. Earnings also improved in recent quarters alongside higher lending activity.
Market Expansion: The Discover acquisition expanded scale and added a proprietary payment network, with payment‑network volume increasing sharply as Capital One debit customers moved onto the Discover rails. Lending and purchase volumes also grew across cards, consumer banking, and auto, indicating broader reach.
Strong Market Position & Advantage: Capital One holds a leading position in U.S. credit cards and consumer banking, becoming the largest U.S. credit card issuer by balances after integrating Discover. This scale, combined with strong transaction activity, supports a durable competitive footprint.
.png)
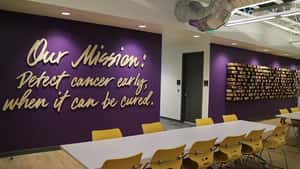
GRAIL is a healthcare company whose mission is to detect cancer early, when it can be cured. GRAIL is using the power of high-intensity sequencing, population-scale clinical studies, and state-of-the-art computer science and data science to enhance the scientific understanding of cancer biology, and to develop and commercialize pioneering products.
GRAIL's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising across 2025 and into 2026, with Galleri driving year-over-year increases and volumes outpacing revenue. Feedback suggests growth accelerated in early 2026 as test adoption broadened.
Strategic Partnerships: Partnerships such as Epic EHR integration and a collaboration with Samsung for Asia expansion are expanding distribution and market access. These relationships also support commercialization through employers, health systems and digital-health channels.
Investor Backing & Capital Strength: A sizable cash balance and recent equity financing provide a substantial runway to fund R&D and commercial expansion. This capital position helps buffer the costs of scaling while regulatory review proceeds.
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: GAAP profitability and improved operating performance are evident, with margins and income strengthening across recent periods. This trend indicates the business is becoming more earnings-efficient even as top-line expansion slows.
Healthy Cash Flow: Consistently strong free cash flow in the latest year and quarter underscores solid cash generation. This provides financial resilience and flexibility while growth initiatives are pursued.
Future-Ready Strategy: Investments in AI-driven operations, autonomous SRE agents, and incident-response automation position the company to capture emerging demand. These offerings create opportunities to deepen adoption with existing customers and attract new ones.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Results indicate broad-based top-line momentum, with operating revenue and recurring revenue both rising strongly year over year. Organic growth is also highlighted, showing that expansion is not solely acquisition-driven.
Market Expansion: Customer numbers increased and international markets, including the U.S., showed accelerated traction. Management outlook points to continued expansion through further investment in key regions.
Healthy Cash Flow: Free cash flow increased alongside growth in adjusted EBITDA. This suggests the business is scaling while continuing to generate solid cash.
Our mission is to remove inefficiency from the foundation of AI. By combining new research in information theory, probabilistic modeling, and distributed systems, we’re creating self-optimizing data infrastructure that continuously improves how information is represented and used by intelligent systems.

Granica's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Investor backing is described as substantial, with the company reporting more than $60M raised and named support from NEA and Bain Capital; CB Insights also records a $45M Series A in 2023. This capital base provides resources to expand products and go-to-market even though it is not a proxy for revenue.
Product Line Growth: The portfolio has expanded from data compression and privacy into Large Tabular Models and Myelin for persistent AI-agent context, with the website citing 4.2B tokens of agent work per day internally. This breadth signals ongoing product development and ambition across the enterprise AI stack.
Strategic Partnerships: Participation in Google Cloud Partner Advantage and availability on AWS and Google Cloud marketplaces enhance enterprise procurement and distribution pathways. These moves indicate progress in market access even if customer counts remain undisclosed.

Treeswift builds physical AI for labor. We use robotics and machine learning to help the people who do real work get more done, starting with the crews who keep the electric grid running,.
Treeswift's Top Stability & Growth Strengths
Market Expansion: Available evidence indicates a deliberate shift from forestry toward electric-utility operations, with use cases now spanning vegetation management, asset inspection, construction, and storm response. Customer-facing materials also describe scaled deployments at major utilities and a larger New York headquarters lease consistent with expansion.
Product Line Growth: Product updates show next‑generation backpack and vehicle data‑collection hardware shipped to customers, expanded species‑identification models, faster data processing, and new planning and construction‑monitoring capabilities. These developments suggest the platform is broadening beyond data capture into decision‑support workflows.
Investor Backing & Capital Strength: The company reports an $11.35 million Series A led by Inspired Capital, with third‑party trackers indicating roughly $16–17 million raised in total. This funding base supports continued product and commercial scaling, even though it is not a proxy for revenue growth.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests quarterly reported sales and organic growth have recently improved, led by the Networks business with 7% organic growth in Q3 2026 and a 6% increase in reported sales to SEK 59.5B. Underlying momentum is also visible year-to-date with 4% organic sales growth through September 2026 despite currency and portfolio effects.
Cost & Operational Efficiency: Feedback suggests margins and efficiency have seen progress, with adjusted gross margin near prior-year levels and prior-year improvements in adjusted EBITA and gross margin indicating disciplined execution. This operational resilience supports stability even when headline revenue is uneven.
Strong Market Position & Advantage: Feedback suggests Ericsson retains a strong competitive footing in mobile network infrastructure, with Networks as a clear growth engine across regions like Japan, India, Vietnam, and the Middle East. The company is viewed as a leading vendor in 5G RAN and core markets, underpinning demand durability.
Rundoo is the AI-native, all-in-one ERP for independent supply stores: point of sale, inventory, payments, and the general ledger in one system. We serve independent paint, hardware, and farm & feed retailers who've been stuck running their business on outdated point-of-sale systems and a patchwork of disconnected software, and we're built to help them modernize: better experiences for them, their...

Rundoo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $30 million Series B led by Battery Ventures, with participation from Bessemer Venture Partners and CRV, brought total announced funding to $48 million, signaling resources and confidence to fuel expansion. The company plans to deploy this capital into engineering in Redwood City and go-to-market expansion in Chicago.
Market Expansion: Availability in Canada with localized tax, payments, and address-lookup, alongside a footprint across the U.S., Canada, and the Caribbean, indicates a growing geographic reach. These moves reflect an intentional push to broaden the addressable market.
Diversified Customer Base: Serving more than 500 independent stores across paint, hardware, lumber, garden centers, and farm-and-feed suggests adoption beyond a single niche. A public client directory lists named businesses across these categories and regions.


Liftoff is a leading AI-powered performance marketing platform for the mobile app economy. Our end-to-end technology stack helps app marketers acquire and retain high-value users, while enabling publishers to maximize revenue across programmatic and direct demand. Liftoff’s solutions, including Accelerate, Direct, Monetize, Intelligence, and Vungle Exchange, support over 6,600 mobile businesses across 74 countries in sectors such as gaming, social, finance,...

Liftoff's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 35% year over year in Q2 2026 to roughly $219–$220 million, marking the eleventh consecutive quarter of growth. Management also guided full-year 2026 revenue to $870–$880 million, extending momentum after approximately 32% growth in 2025.
Healthy Cash Flow: Trailing twelve‑month operating cash flow increased about 90% to $237 million and free cash flow rose 142% to $184 million as of Q2 2026. These gains indicate that expanding revenue is converting into stronger cash generation.
Investor Backing & Capital Strength: The company completed a Nasdaq IPO in 2026 and previously secured a minority investment from General Atlantic at a multi‑billion‑dollar valuation. These milestones suggest strengthened access to capital alongside continued scaling of its advertising platform.

Deepgram is the leading voice AI platform for developers building speech-to-text (STT), text-to-speech (TTS) and full speech-to-speech (STS) offerings. 200,000+ developers build with Deepgram’s voice-native foundational models – accessed through APIs or as self-managed software – due to our unmatched accuracy, latency and pricing. Customers include software companies building voice products, co-sell partners working with large enterprises, and enterprises solving...

Deepgram's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue was described as doubling annually into 2025, with separate market analysis estimating roughly $100M in annualized revenue by mid-2026. The company also indicated it entered 2025 cash-flow positive, underscoring momentum in the business.
Investor Backing & Capital Strength: A $130 million Series C at a $1.3 billion valuation drew new strategic investors alongside existing backers, signaling deep capital support for scaling. Independent coverage also notes total funding exceeding $215 million, reinforcing financial flexibility for expansion.
Market Expansion: International reach expanded with plans for Europe and Asia and a Singapore regional hub, alongside reported strong growth in regional API demand. Product scope also widened from transcription into text-to-speech, real-time voice agents, and an industry entry via the OfOne acquisition.
EliseAI builds vertical AI agents for housing and healthcare — sectors that together make up nearly 40% of household spending. These agents automate high-volume workflows like leasing, maintenance, renewals, and patient intake, helping organizations cut costs, improve efficiency, and deliver better experiences. How does it work? EliseAI integrates directly into operational workflows: Housing: Manages leasing, maintenance, renewals, billing, and resident communication. Healthcare: Handles intake,...
EliseAI's Top Stability & Growth Strengths
Strong Revenue Growth: Reported ARR surpassed $200 million in June 2026 with five consecutive years of 100% year-over-year growth, indicating rapid scaling. Adoption breadth, including claims of powering one in six U.S. apartments, reinforces the commercial momentum behind that trajectory.
Investor Backing & Capital Strength: A $350 million round in September 2026 at a $4 billion valuation, with major existing investors participating alongside Ontario Teachers’ Pension Plan, underscores substantial access to capital. This financing signals strong confidence to fund continued product development and go-to-market expansion.
Market Expansion: Reach reportedly grew from about one in twelve U.S. apartments in 2024 to one in six in 2026, alongside plans for a second engineering hub in San Francisco. The company is also expanding from leasing into broader property-management workflows and healthcare administration.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have progressed from more than $300 million in June 2025 to more than $400 million by May 2026, signaling clear top-line momentum. Growth among higher‑spend enterprise accounts is also highlighted as a key contributor.
Investor Backing & Capital Strength: An $800 million equity and strategic financing round at an approximately $2.4 billion valuation is described as providing substantial capacity to fund expansion. Ongoing sponsorship by the controlling shareholder is also noted.
Product Line Growth: AI-led offerings such as Edwin AI are described as contributing a significant share of bookings with very rapid recurring‑revenue growth. The Catchpoint acquisition further extended capabilities into internet performance and digital experience monitoring.
Superhuman (formerly Grammarly) is the AI productivity platform on a mission to unlock the superhuman potential in everyone. The Superhuman suite of apps and agents brings AI wherever people work, integrating with over 1 million applications and websites. The company’s products include Grammarly’s writing assistance, Docs’ connected surface for teams, Mail’s inbox management, and Go, the proactive AI assistant that...
Superhuman's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue at the original email business is described as rising from roughly $30M ARR at the end of 2024 to about $35M by mid-2025, based on independent estimates. This points to solid momentum ahead of the acquisition.
Product Line Growth: The company broadened its suite beyond Mail to include Grammarly, Docs, and Go, and added meeting intelligence via the Fathom acquisition. This expansion indicates intentional widening of use cases and monetization paths.
Market Expansion: A new Seattle office with capacity for additional headcount and stated plans to keep hiring reflect continued geographic and workforce build-out. The organization also reports a large global team, underscoring operational scale.
Founded in 2020 by George Sivulka and backed by Peter Thiel and Andreessen Horowitz, Hebbia powers investment decisions for BlackRock, KKR, Carlyle, Centerview, and 40% of the world’s largest asset managers. Our flagship product, Matrix, delivers industry-leading accuracy, speed, and transparency in AI-driven analysis. It is trusted to help manage over $15 trillion in assets globally. We deliver the intelligence that...

Hebbia's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from roughly $13M in 2024 to nearly $50M by 2026, and recent updates note new ARR tripling quarter over quarter. These signals point to substantial top-line acceleration over the last two years.
Market Expansion: EMEA revenue reportedly grew 373% year over year from FY2025 to FY2026, with plans to triple the regional team and more than double account executives. This combination of sales momentum and hiring suggests widening international reach.
Strong Market Position & Advantage: Major financial institutions are adopting the platform at scale, including a Morgan Stanley deployment covering about 5,000 workers and broad use among top asset managers with many production use cases. High usage levels (e.g., crossing 1 billion pages processed) indicate deeper embedment in enterprise workflows.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
Vannevar combines Silicon Valley innovation with former special operators to build AI for real-world national security outcomes. Since our founding in 2019, Vannevar has deployed its technology across 125 missions, safeguarding our service members and improving our country's deterrence. We believe our military service members and intelligence officers deserve access to the best technology American innovation can offer, and we are...

Vannevar's Top Stability & Growth Strengths
Strong Revenue Growth: Company-reported figures indicate scale to roughly $80 million in 2024 annual contract value and recognition on the Inc. 5000 list for rapid multi-year expansion. Government contract obligations under a production vehicle and continued awards further reflect meaningful commercial momentum, even as contract ceilings are not revenue.
Profitability: The business is described as having achieved three consecutive profitable years while expanding contract value. This points to growth supported by operating discipline rather than reliance solely on external financing.
Market Expansion: A transition from a DIU prototype to a production-scale agreement and reported deployment across all U.S. military branches and combatant commands indicate widening reach within the defense market. Partnerships and authorizations announced in 2026 are positioned to extend access across combatant commands and federal agencies.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded from roughly $1.9B in 2024 to $5.1B in 2025, with mid-2026 quarterly revenue still rising sharply. A very large revenue backlog of about $104B and additional net new commitments point to continued demand.
Strong Market Position & Advantage: The company is described as a leading specialist in AI-focused cloud infrastructure, supported by major contracts and third-party recognition. This advantage is reinforced by large-scale GPU capacity and adoption across AI labs, hyperscalers, and enterprises.
Strategic Partnerships: Relationships with NVIDIA and multiyear agreements with organizations such as Meta and Anthropic underpin access to advanced hardware and sizeable workloads. These alliances appear to support capacity build-out and commercial visibility.
.png)
American medicine is the best in the world. But the American healthcare system is challenged by high administrative costs that burden patients, health systems, and insurance companies with unnecessary expenses. We are focused on addressing those challenges. We use GenAI to improve the most pressing financial pain points in the revenue cycle. We’re one of the first companies to deploy GenAI...
AKASA's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests AKASA reports more than tenfold growth since mid-2024 and nearly sixfold year-over-year inpatient volume processed, indicating rapid commercial traction and usage expansion.
Market Expansion: Feedback suggests deployments have broadened across major U.S. health systems, with a footprint reportedly spanning roughly 500 hospitals and customers representing about 10% of U.S. inpatient discharges.
Investor Backing & Capital Strength: Feedback suggests AKASA has attracted substantial capital, with reported total funding around $200M+, providing resources to scale products and partnerships.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financial results highlight sustained top-line expansion with rising quarterly revenue and management increasing full‑year guidance, indicating momentum across 2025 and into 2026.
Diversified Revenue Streams: Growth is coming from both diagnostics and data licensing/AI applications, with testing volumes and data contracts expanding rather than reliance on a single line of business.
Customer Loyalty & Retention: Reported net revenue retention above 100% and sizable remaining contract value suggest existing pharmaceutical customers are deepening engagements.



