

Top Tech Companies in San Francisco Bay Area, CA (10,000+)
We bring brilliant people together in a global ecosystem that is sparking the world’s potential. Arm technology enables specialized processing built on the economics, design freedom and accessibility of general-purpose compute that has, so far, led to more than 180 billion chips being shipped by our partners.

Arm's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reached $4.92B in FYE26 with a third consecutive year of 20%+ growth and a record $1.49B quarter. Q1 FYE27 rose 22% year over year to $1.29B, with record first‑quarter licensing and royalties.
Market Expansion: Royalty strength is being propelled by expanding data‑center and AI deployments, with data‑center royalties more than doubling year over year and hyperscaler CPU adoption increasing. Broader uptake of Armv9 and Compute Subsystems is lifting royalty rates across cloud, smartphone, and edge markets.
Product Line Growth: The launch of Arm’s first production data‑center processor (AGI CPU) opens a new revenue vector beyond IP licensing. Management reports demand exceeding $2B across FYE27–FYE28, indicating early commercial traction.
Proto is the leader for inclusive multilingual contact centre automation. Governments and businesses use Proto's AI Customer Experience (AICX) platform to ensure local language service, long-term operational efficiency, and citizen protection. Proto deployments are powered by its HermesAI™ engine for local and mixed languages.
Proto's Top Stability & Growth Strengths
Market Expansion: Geographic reach is extending via deployments with regulators, airports, banks, and clinics across Africa and Southeast Asia, supported by country-level resellers in Namibia and the Philippines. Public references include Rwanda’s central bank “Intumwa” and Philippine programs such as USSC, indicating broader distribution beyond direct sales.
Product Line Growth: Product capability has expanded with voice AI for underserved languages (e.g., Tagalog, Cebuano, Kinyarwanda, Oshiwambo) and a 2026 cadence of new features like workflow versioning, database connectivity, redesigned agents, and a Voice API. These launches signal continued R&D and feature growth into 2026.
Strategic Partnerships: A visible ecosystem featuring Africa’s Talking, Eclectics, Gates Foundation, AWS, NVIDIA, and regional partners like Apex Business Solutions (Namibia) and Xymbolic (Philippines) is widening go-to-market reach. These collaborations support distribution and delivery across multiple countries and sectors.
We bring together one of the world’s largest libraries of multimodal clinical and molecular data with a robust suite of AI tools to help physicians personalize care in real time, connect patients with therapies and clinical trials, and enable partners to accelerate discovery and development of new treatments. With ~8 million de-identified research records and 350+ petabytes of data, Tempus partners...
Tempus AI's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue expanded rapidly, with FY2025 up 83% to about $1.27B and Q1/Q2 2026 up 36% and 22% year over year, respectively. Management also raised 2026 revenue guidance to approximately $1.595–$1.605B.
Diversified Revenue Streams: Both Diagnostics and Data & Applications are expanding, with Diagnostics up 34.7% in Q1 and 20% in Q2 2026 and Insights/data licensing up 36% in Q2 alongside about $200M in new licenses. Rising oncology test volumes (28–31% YoY) and accelerating MRD tests (~4,700 in Q4 2025 to ~9,000 in Q2 2026) reinforce multiple growth engines.
Profitability: The company achieved its first GAAP-profitable quarter in Q2 2026 (net income about $5.6M; Adjusted EBITDA ~$8.0M). Guidance points to further improvement in 2026, indicating progress toward sustained profitability.
.png)
American medicine is the best in the world. But the American healthcare system is challenged by high administrative costs that burden patients, health systems, and insurance companies with unnecessary expenses. We are focused on addressing those challenges. We use GenAI to improve the most pressing financial pain points in the revenue cycle. We’re one of the first companies to deploy GenAI...
AKASA's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A third funding round reported as a Series C in June 2024, bringing total raised to $200M+, is presented as a scaling‑stage milestone and foundation for continued investment. This capital base aligns with ongoing product rollouts and market expansion efforts.
Strategic Partnerships: Cleveland Clinic expanded its enterprise deployment in 2025, and the Clinic’s own materials later highlighted systemwide use of AKASA’s generative‑AI tools for coding and documentation across U.S. locations. These multi‑site, referenceable wins indicate traction with major health systems.
Product Line Growth: Successive mid‑cycle launches in 2024–2025 (e.g., Authorization Advisor, AKASA Medical Coding, CDI Optimizer) highlight continued R&D and commercialization. This expansion signals a broader roadmap beyond an initial single‑product focus.
SentiLink is the leading fraud intelligence company, providing financial institutions and fintechs with purpose-built solutions for identity verification and fraud prevention. Our products detect synthetic fraud, identity theft, and hard-to-detect first-party fraud in real time — helping partners stop losses before they happen while approving more legitimate customers. Founded in 2017 by Naftali Harris and Max Blumenfeld, creators of the risk...

SentiLink's Top Stability & Growth Strengths
Strategic Partnerships: Availability of SentiLink’s Identity Theft Score on the FICO Marketplace broadens distribution to FICO Platform customers, and a 2026 FICO Industry Vanguard Decision Award signals traction within bank decisioning ecosystems. Being listed on FICO Marketplace also lowers integration friction for institutions already on FICO.
Market Expansion: Selection by Florida’s Agency for Health Care Administration to support the state’s 2026 Medicaid Integrity Initiative marks expansion into public‑sector healthcare use cases. Coupled with wider distribution via FICO, this points to simultaneous vertical (government/healthcare) and horizontal (channel) expansion.
Strong Hiring & Retention: Active postings across engineering, data, and leadership roles—and third‑party trackers showing “actively hiring” status—indicate headcount growth in mid‑2026. The February 2026 appointment of a Chief Revenue Officer underscores an explicit push to scale sales and partnerships.

Sortly is the simplest inventory platform for business and teams to stay on top of their stuff. Our visual system enables business to easily track what they have, where it is, and who has it. Anytime, anywhere, on any desktop, tablet or mobile device. Sortly is trusted by tens of 1000’s of small businesses and teams at large enterprises including HP, Honeywell,...

Sortly's Top Stability & Growth Strengths
Strong Revenue Growth: Company materials describe an ambition to scale from roughly $20M to $50M ARR, with earlier milestones around eight‑figure ARR and recent hiring and distribution signals consistent with expansion. Conflicting third‑party estimates are noted, but the stated ARR trajectory and activity point to upward momentum.
Profitability: Company pages state the business is profitable while pursuing ARR expansion, indicating a level of financial stability that can support ongoing product and go‑to‑market investment. This posture aligns with a bootstrapped, operations‑funded growth narrative referenced across materials.
Strategic Partnerships: Amazon Business featured Sortly and promotes a joint workflow, expanding reach into business buyers and creating a channel that often correlates with pipeline growth. Such distribution exposure complements the company’s SMB‑focused go‑to‑market.
CoreWeave, the AI Hyperscaler™, delivers a cloud platform of cutting-edge software powering the next wave of AI. The company's technology provides enterprises and leading AI labs with cloud solutions for accelerated computing. Since 2017, CoreWeave has operated a growing footprint of data centers across the US and Europe. CoreWeave was ranked as one of the TIME100 most influential companies and...

CoreWeave's Top Stability & Growth Strengths
Strong Revenue Growth: Reported revenue rose from $1.9B in 2024 to $5.1B in 2025, with early‑2026 quarters continuing triple‑digit year‑over‑year increases. These disclosures indicate a steep, ongoing acceleration in scale.
Strategic Partnerships: Multi‑year, multi‑billion‑dollar agreements with Meta, Anthropic, Jane Street, and expanded OpenAI commitments point to durable, large‑scale utilization. A deepened NVIDIA collaboration, including early deployments of GB200/GB300 and plans to accelerate AI “factory” buildouts, supports access to cutting‑edge capacity.
Investor Backing & Capital Strength: Significant financing and market recognition—including a $1.1B Series C, large credit and notes facilities, and inclusion in the Nasdaq‑100—underscore strong capital access. This funding underpins rapid data‑center expansion and GPU procurement.
Celonis makes processes work — for people, companies, and the planet. Powered by process mining and AI, the Celonis Process Intelligence Platform integrates process data and business context to create a living digital twin of business operations. We enable thousands of companies worldwide to understand how their business actually runs and, together with their partners, build intelligent solutions that transform...

Celonis's Top Stability & Growth Strengths
Strong Market Position & Advantage: Independent market-share analysis places Celonis at the front of its category while the market itself expands. This positioning suggests the company is capturing growth in a segment it leads.
Future-Ready Strategy: External recognition for long-term growth potential signals confidence in Celonis’s strategy, innovation, and talent pipeline. This points to preparedness as the space broadens from process mining into process intelligence and AI-enabled workflows.
Strategic Partnerships: A new alliance with a major data and AI platform provider expands product integrations and go-to-market reach into enterprise AI workflows. Such ecosystem momentum supports broader adoption and commercial expansion.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising briskly, with the latest quarter up year over year and full‑year FY2026 guidance raised for both revenue and ARR. Prior billings and deferred revenue growth indicate healthy demand heading into FY2026.
Strong Market Position & Advantage: Independent analyst evaluations place the company as a leader in SSE/SASE and note frequent inclusion on enterprise shortlists. A broad global footprint and regulatory certifications bolster competitiveness in regulated and international markets.
Product Line Growth: Expansion in newer offerings—such as Data Security, AI‑focused modules, and Zero Trust Branch—shows meaningful traction. Metered, non‑seat‑based solutions accounted for a sizable share of new ACV, suggesting broader monetization beyond core seats.

Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Diversified Revenue Streams: Growth engines in wireless, streaming, and parks are expanding, with management emphasizing six growth drivers that now comprise a majority of revenue. The May 2025 opening of Epic Universe and continued wireless momentum add distinct contributors that help offset legacy declines.
Profitability: Peacock reached its first-ever quarterly profit in Q2 2026 as paid subscribers climbed to roughly 48 million, signaling improved streaming economics. This milestone adds a profitable component within the portfolio alongside resilient parks performance tied to Epic Universe.
Healthy Cash Flow: Free cash flow was about $4.6 billion in Q2 2026, supporting ongoing investment and capital returns. This cash generation provides flexibility as the company pivots its broadband approach and scales newer growth engines.
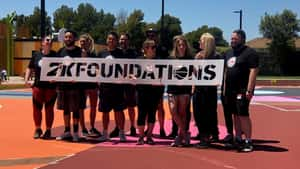
2K is headquartered in Novato, California and is a wholly owned label of Take-Two Interactive Software, Inc. (NASDAQ: TTWO). Founded in 2005, 2K Games is a global video game company, publishing titles developed by some of the most influential game development studios in the world. Our studios responsible for developing 2K’s portfolio of world-class games across multiple platforms, include Visual...
2K's Top Stability & Growth Strengths
Strong Revenue Growth: Filed FY2026 results list NBA 2K25/2K26, WWE 2K26, and Borderlands 4 among the largest revenue contributors, indicating multiple 2K titles materially lifted the parent’s top line. Company materials also underscore 2K’s role as a major revenue engine within Take-Two during this period.
Product Line Growth: The Gearbox acquisition in June 2024 moved Borderlands/Tiny Tina under 2K and expanded owned franchises, while filings show an active slate including Mafia: The Old Country, Borderlands 4, NBA 2K26/27, and WWE 2K26. This reflects a broader portfolio and sustained output.
Strong Market Position & Advantage: NBA 2K26 finished as the best-selling sports game in the U.S. for 2025, and WWE 2K routinely charts among top sellers, signaling durable franchise pull. Label-level importance is reinforced in FY2026 filings that highlight NBA 2K, Borderlands, and WWE 2K as leading franchises.
Rubrik (NYSE: RBRK), the Security and AI Operations Company, leads at the intersection of data protection, cyber resilience, and enterprise AI acceleration. Rubrik Security Cloud delivers complete cyber resilience by securing, monitoring, and recovering data, identities, and workloads across clouds. Rubrik Agent Cloud accelerates trusted AI agent deployments at scale by monitoring and auditing agentic actions, enforcing real-time guardrails, fine-tuning...

Rubrik's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly across recent periods, with FY2026 results and the subsequent quarter both showing sharp year-over-year increases and strong subscription-led momentum. Management raised the FY2027 outlook following the latest quarter, underscoring continued demand.
Healthy Cash Flow: Free cash flow is meaningfully positive and improving at scale, including a healthy margin in Q1 FY2027 and a large year-over-year increase in FY2026. Improving subscription contribution margins indicate growing operating leverage.
Strong Market Position & Advantage: Independent analyst recognitions place the company among market Leaders for backup/data protection and cyber recovery, often highlighted for vision. Expanding large-customer cohorts and post-IPO scale further reinforce competitive standing.
We solve for advertising campaign and creative complexities - both key elements to the time/money savings and performance that brands, agencies and businesses seek. Our unified platform combines media, creative, and intelligence, offering end-to-end workflows powered by AI across the open and closed web. With over 700 brands and advertisers, we've proven that dynamic and personalized creative makes advertising impactful. We...
Smartly's Top Stability & Growth Strengths
Product Line Growth: Recent launches, including the Smartly Synapse AI orchestration layer and integrations with Amazon DSP and Roku Ads API, broaden the platform’s capabilities across CTV and cross‑channel activation. These moves indicate ongoing investment to expand the offering in 2026.
Strategic Partnerships: An expanded partnership with Horizon Media—becoming the first SaaS activation partner for Blu audience segments—signals increasing enterprise adoption. Company updates through mid‑2026 also highlight deepening ties with agencies and major platforms.
Market Expansion: A new product, engineering, and commercial hub opened in Mexico City in March 2026 demonstrates continued investment in global operations. Company materials cite support for 800+ brands and $6–7B in managed ad spend globally, suggesting a larger footprint than prior years.
A global leader in applied safety science, UL Solutions transforms safety, security and sustainability challenges into opportunities for customers in more than 100 countries. UL Solutions delivers testing, inspection and certification services, together with software products and advisory offerings, that support our customers’ product innovation and business growth. The UL Certification Marks serve as a recognized symbol of trust in...

UL Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show full-year 2025 revenue of about $3.05B up roughly 6% year over year, with Q1 2026 up 7.5% and Q2 2026 up ~5% year over year alongside mid‑single‑digit organic gains. Consistent quarterly execution through 2025 underscores steady top‑line momentum.
Profitability: Management reported record revenue with “impressive margin expansion” in Q2 2026, and adjusted EBITDA margin expanded earlier in 2026. Strong operating cash generation in 2025 further supports the improving earnings profile.
Innovation-Driven Growth: New launches such as AI‑enabled sustainability software (ULTRUS 360), building‑compliance software, and certifications for AI‑enabled products and hydrogen fueling components indicate investment in adjacent, faster‑growing niches. These moves align the portfolio with regulation‑ and sustainability‑driven demand.
Rundoo is the AI-native, all-in-one ERP for independent supply stores: point of sale, inventory, payments, and the general ledger in one system. We serve independent paint, hardware, and farm & feed retailers who've been stuck running their business on outdated point-of-sale systems and a patchwork of disconnected software, and we're built to help them modernize: better experiences for them, their...

Rundoo's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A late‑August 2026 $30M Series B led by Battery Ventures brought total funding to about $48M and is earmarked for team expansion and product development. Cross‑source consistency on the round and totals supports available runway for execution.
Strategic Partnerships: The company highlights growing integrations and partnerships with major distributors and buying groups across hardware, paint, farm/feed, and lawn/garden, including collaboration within the Benjamin Moore dealer ecosystem. These connections extend reach in target channels and embed the platform deeper in independent retail workflows.
Market Expansion: Recent reporting cites “more than 500” independent supply stores across the U.S., Canada, and the Caribbean using the platform. Active roles across engineering and go‑to‑market in Redwood City and Chicago indicate widening regional coverage.

CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 26% year over year to $1.39B in Q1 FY2027, while ARR grew 24% to $5.51B with record net new ARR. Management also raised FY2027 revenue and ARR guidance, indicating confidence in continued double‑digit expansion.
Profitability: GAAP profitability was achieved in Q1 FY2027 (diluted EPS $0.11) alongside higher non‑GAAP earnings, reflecting operating leverage at scale. Prior periods also highlighted improving profit metrics, reinforcing an upward profitability trend.
Healthy Cash Flow: Cash generation reached record levels in Q1 FY2027 with $591M in operating cash flow and $468.5M in free cash flow. FY2026 likewise set records for operating and free cash flow, underscoring durable unit economics.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Profitability: Operating margins remain high, indicating sustained efficiency even as top‑line growth stays modest. Management commentary emphasizes maintaining strong margin discipline through 2026.
Healthy Cash Flow: Cash generation is robust, with sizable quarterly free cash flow and higher full‑year targets underscoring balance‑sheet flexibility. Capital returns and liquidity headroom support ongoing investment despite subdued growth.
Future-Ready Strategy: AI-led initiatives such as Dash and embedding intelligence into the core product signal a pivot toward next‑generation workflows. Ongoing rollouts and integrations point to a roadmap designed to reaccelerate growth over time.
Founded in 2015 by former NSA cyber operators, Huntress protects all businesses—not just the 1%—with enterprise-grade, fully owned and managed cybersecurity products at the price of an affordable SaaS application. The Huntress difference is our One Team advantage: our technology is designed with our industry-defining Security Operations Center (SOC) in mind and is never separated from our service. We protect...

Huntress's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported as surpassing $250M in ARR with rapid year‑over‑year expansion, and inclusion on Deloitte’s Technology Fast 500 points to sustained multi‑year momentum. Company communications also trace a clear trajectory from near‑$100M ARR in mid‑2024 to $250M+ by mid‑2026.
Investor Backing & Capital Strength: Capital access is underscored by a $150M Series D at roughly a $1.55B valuation, with indications the company is evaluating another raise at a higher valuation. Management states the funding is being used to fuel product launches and geographic/channel expansion.
Market Expansion: Customer and channel reach are expanding, with protection extended to hundreds of thousands of businesses across 100+ countries and new distribution partners added to scale in the mid‑market, public sector, and EMEA. Acquisitions and portfolio additions support entry into adjacent segments and broader international coverage.

In 1939, Bill Hewlett and Dave Packard, college friends turned business partners, started the original Silicon Valley startup in the space of a rented Palo Alto garage. Starting with audio oscillators, the friends built the foundation for a company that would grow to become a global leader in enterprise technology. More than 75 years later, our success is exemplified through...
Hewlett Packard Enterprise's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is at record levels with a strong year-over-year increase, and management has materially raised near‑term and next‑year growth outlooks on the back of robust Cloud & AI and Networking demand. Large order backlogs underscore momentum across core segments.
Profitability: Operating profit has expanded to record levels alongside stronger sales, and capital returns have increased. Management also signaled higher free cash flow for the year, pointing to improved margin and cash generation.
Strong Market Position & Advantage: The company is recognized as a Leader in key categories such as enterprise storage and wired/wireless LAN, and highlights sustained leadership in supercomputing. A broad global customer base and the GreenLake hybrid cloud platform reinforce competitive positioning across edge‑to‑cloud infrastructure.
Our mission is to remove inefficiency from the foundation of AI. By combining new research in information theory, probabilistic modeling, and distributed systems, we’re creating self-optimizing data infrastructure that continuously improves how information is represented and used by intelligent systems.

Granica's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital is described as robust, with a $45M Series A in June 2023 led by NEA and Bain Capital Ventures and the company now stating it has raised “more than $60M.” These signals indicate a larger capital base supporting continued build‑out across funding, product, customers, and hiring.
Product Line Growth: The offering has expanded from Crunch and Screen to include Chronicle and the 2026 launch of Myelin with multiple deployment options and efficiency claims (e.g., context resumed from cache). An active research program with publications up to ICLR 2026 suggests sustained R&D tied to the roadmap.
Strategic Partnerships: Participation in Google Cloud Partner Advantage and availability on Google Cloud Marketplace and AWS Marketplace extend reach within major cloud ecosystems. These channels are presented as enabling easier integration within existing customer environments.



