

Top Tech Companies in San Francisco Bay Area, CA (10,000+)
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has scaled to over $1.2B with continued double-digit quarterly increases and an outlook nearing $1.5B, indicating sustained momentum. Guidance increases reinforce the trajectory of ongoing top-line expansion.
Market Expansion: International revenue is growing faster than the overall business and now represents a significant share of total revenue, with customers across more than 100 countries. The customer base surpassing 205,000 underscores broader geographic reach and upmarket penetration.
Customer Loyalty & Retention: Net revenue retention remains above 100%, suggesting existing customers are expanding spend through cross-selling and wider platform adoption. Larger-account cohorts are growing rapidly, including rising counts of $50K+ and $1M+ ARR customers.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating profitability is strengthening, with Q2 2026 delivering a 27% adjusted operating margin and 65% growth in adjusted diluted EPS. For 2025, operating income also rose to $1.7B, highlighting improved earnings leverage.
Resilient & Sustainable Growth: Gross profit increased every year from 2021 to 2025 and accelerated 25% year over year in Q2 2026. Management raised its 2026 gross-profit outlook to $12.51B (about 21% growth), reinforcing a multi-period expansion trend.
Cost & Operational Efficiency: Efficiency measures and AI-driven execution are associated with faster product delivery and improved profitability. Workforce streamlining and operating leverage supported margin expansion alongside growth in both Cash App and Square.
.png)
Hex is changing the way people work with data. Our platform makes analytics workflows more powerful, collaborative, and shareable. Hex solves key pain points with today's data and analytics tooling, and is loved by thousands of users all over the world for the beautiful UI, new superpowers, and boundless flexibility. We are a tight-knit crew of engineers, designers, and data aficionados....

Hex's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Recent financing momentum is evident, with a $70M Series C in May 2025 led by Avra and participation from firms such as Andreessen Horowitz, Sequoia, Redpoint, and Snowflake Ventures. This capital is positioned to support further product and go-to-market expansion while signaling confidence in the company’s trajectory.
Market Expansion: Customer adoption appears to be broadening from more than 1,500 teams in May 2025 to more than 2,000 customers globally, including enterprises like Reddit, Figma, HubSpot, Rivian, and Anthropic. Evidence of scaling usage, such as hundreds of millions of usage-based billing events and increased adoption of advanced compute add-ons, reinforces this expansion.
Innovation-Driven Growth: Product momentum centers on AI-powered analytics and agentic workflows, including features like the Notebook Agent and moves into embedded analytics. The acquisition of Hashboard and introduction of usage-based monetization for advanced compute suggest continued innovation aligned with market shifts.
 (1).png)
Hedra is an AI native platform for multimodal creation. The platform is built around their own cutting-edge proprietary video model, Character-3, which is the first multimodal model in production. Alongside Character-3, the platform also brings other leading foundation models into one ecosystem spanning generative images, video, and audio. Prosumer and enterprise users leverage Hedra to generate content ranging from viral...

Hedra's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Available information indicates Hedra secured a $32M Series A in May 2025, bringing total disclosed funding to roughly $44M and signaling capacity to scale operations. This financing, corroborated by independent reporting, points to strong investor confidence.
Product Line Growth: The company expanded beyond character-video into a broader visual-AI platform with enterprise tools, Teams plans, APIs/SDKs/CLI, and inference infrastructure. These launches suggest sustained product investment and a widening solution footprint.
Market Expansion: Company materials report 20M+ users, 125K+ businesses, and 45M+ content generations, alongside growing API usage. This points to broader commercial reach across creators, teams, and developers.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
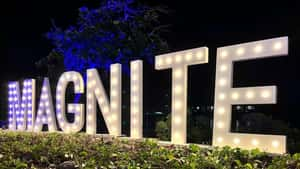
Magnite's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising steadily, including 11% year-over-year growth to $192.8 million in Q2 2026 and 7% growth for full-year 2025. The step-up from 6% growth in Q1 2026 to 11% in Q2 indicates accelerating momentum.
Profitability: Adjusted EBITDA increased 30% year over year in Q2 2026 as margin expanded from 34% to 37%, signaling operating leverage. Net income also improved to $19.4 million from $11.1 million year over year in that quarter.
Healthy Cash Flow: Guidance points to free-cash-flow growth in the high-40% range for 2026 alongside adjusted EBITDA growth of more than 20%. Operating cash flow reached $57.4 million in Q2 2026.
Atlassian creates teamwork solutions for high-performing teams. Our portfolio of collaboration and work management software products includes Jira, Confluence, Trello, Loom and Rovo. More than 300,000 businesses worldwide rely on Atlassian’s technology, including 80 percent of Fortune 500 companies. Our solutions support various business teams and they help organizations plan, track, and deliver their biggest ideas together.
Atlassian's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased over recent fiscal years, with the latest results showing faster top-line momentum. Cloud sales expanded more quickly than the overall business, reinforcing this trajectory.
Customer Loyalty & Retention: Net revenue retention above 100% and rising subscription ARR indicate existing customers are expanding spend and renewing at healthy levels. Growth in higher-value cloud cohorts and larger contracted obligations add visibility.
Innovation-Driven Growth: Expansion into AI-assisted teamwork and enterprise service management is driving additional adoption and cross-sell alongside core products. Early traction for offerings like Rovo suggests multiple vectors beyond new-customer acquisition.

At Revel, we are revolutionizing the way the world’s most critical hardware is controlled—across aerospace, automotive, energy, and manufacturing sectors. Our next-generation software stack combines an intuitive command/control interface, a specialized programming language tailored for hardware control, and a high-performance runtime environment. We empower engineers to build, test, and deploy critical systems rapidly, reliably, and safely.

Revel's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $150 million Series B in February 2026 led by Index Ventures, with participation from Redpoint and existing investors, indicates substantial financial support for scaling. This capital follows earlier funding and is intended to fuel hiring, product development, and broader deployments across aerospace, defense, robotics, and industrial markets.
Market Expansion: The company is expanding from aerospace test software into broader industrial control, targeting energy, nuclear, water treatment, defense, data centers, and manufacturing. Named deployments and case studies in areas like nuclear energy (e.g., Aalo Atomics) support this strategic broadening.
Strong Hiring & Retention: Reported headcount growth from 18 (September 2025) to 59 (August 2026), alongside plans for 100+ openings and new product teams in mid‑2026, reflects aggressive team scaling. This organizational build‑out underpins capacity for increased customer deployments and product lines such as RevelTest and RevelC2.
Biotechnology is rewriting life as we know it, from the medicines we take, to the crops we grow, and the household goods that we rely on every day. But moving at the new speed of science requires better technology. Benchling’s mission is to unlock the power of biotechnology. The world’s most innovative biotech companies use Benchling’s R&D Cloud to power the...
Benchling's Top Stability & Growth Strengths
Strong Revenue Growth: Evidence points to ARR reaching about $210M with continued year-over-year increases, and company statements indicate surpassing $200M in annualized revenue. Feedback suggests upselling and higher average revenue per customer support expansion from existing accounts.
Market Expansion: Adoption reportedly grew from ~410 customers in 2020 to 1,200+ by 2024, with 240 new customers added in 2024 and penetration into top-50 global biopharma firms. Feedback suggests partnerships and geographic breadth bolster reach across biotech and pharma.
Innovation-Driven Growth: Product launches in AI, automation, and broader R&D workflows, plus acquisitions and collaborations (e.g., Lilly TuneLab, NVIDIA) indicate active investment in next-generation capabilities. Feedback suggests these moves expand use cases and deepen platform integration in labs.

Gusto is a modern, online small business platform that helps small businesses take care of their teams. On top of full-service payroll, Gusto offers health insurance, 401(k)s, expert HR, and team management tools. Today, Gusto offices in Denver, San Francisco, and New York serve more than 400,000 businesses. Our customers come from all walks of life, and so do we. We...
Gusto's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue for the trailing 12 months was announced above $1 billion, with five consecutive quarters of accelerating growth reported by leadership. These milestones indicate renewed momentum and continued top-line expansion into 2026.
Healthy Cash Flow: The company is described as cash-flow positive for several years, signaling capacity to fund operations and investments internally. This supports ongoing growth without heavy reliance on new primary financing.
Product Line Growth: Expansion beyond payroll into benefits, retirement, financial services, compliance, AI tools, and acquisitions (e.g., Guideline, Mosey) is widening monetization paths. Announced waves of product updates in 2026 reinforce an expanding platform scope.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.
We started a movement in which everyone can win – shoppers, retailers, society and every person on our team. To play fair, trust people and reward them for doing the right thing. We see and feel the impact of our work as more and more people gain financial freedom and retailers grow across the globe. Founded seven years ago in Sydney,...
Afterpay's Top Stability & Growth Strengths
Strong Revenue Growth: Afterpay-related revenue increased in Block’s latest reporting, with Afterpay Post-Purchase contributing higher year-over-year dollars in Q2 and the first half of 2026. Filings indicate the BNPL product is scaling within the parent company’s results.
Strong Market Position & Advantage: Independent estimates place Afterpay/Block in a leading position in U.S. BNPL issuance and Pay-in-4 lending. This standing suggests competitive advantage as the service expands into more everyday spending categories.
Customer Loyalty & Retention: Company materials describe the vast majority of gross merchandise value coming from returning customers. This repeat usage points to durable engagement across its merchant network.
Cisco ThousandEyes is a Digital Experience Assurance platform that empowers organizations to deliver flawless digital experiences across every network – even the ones they don’t own. Powered by AI and an unmatched set of cloud, internet and enterprise network telemetry data, ThousandEyes enables IT teams to proactively detect, diagnose, and remediate issues – before they impact end- user experiences. ThousandEyes...
Cisco ThousandEyes's Top Stability & Growth Strengths
Strong Revenue Growth: Cisco’s filings indicate its Observability category is expanding, with ThousandEyes explicitly cited as a contributor to that growth. More recent updates also describe year-over-year increases for the category, reinforcing ThousandEyes’ positive revenue impact.
Product Line Growth: Ongoing releases such as AI-enabled workflows, Traffic Insights, and deeper integrations (including with Splunk) broaden ThousandEyes’ capabilities. Additions like Connected Devices and expanded cloud visibility move the product beyond traditional network monitoring into wider assurance use cases.
Market Expansion: ThousandEyes is being extended across Cisco’s ecosystem and into service-provider scenarios, increasing its reach beyond conventional enterprise IT teams. Expanded distribution through Cisco networking and observability portfolios creates additional cross-sell pathways.
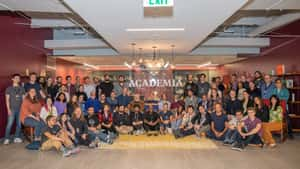
Academia.edu is the world’s leading platform for researchers and scholars to share their work, discover research and connect with fellow academics globally. Our bold vision: to democratize and accelerate the world's research, enhancing the speed of scientific discovery and technological progress for the benefit of everyone. We imagine a world where accessing academic papers is effortless, keeping track of cutting-edge...
Academia.edu's Top Stability & Growth Strengths
Strong Market Position & Advantage: The platform is recognized as a leading academic social network alongside ResearchGate, with very large reported membership and substantial web visibility (e.g., an estimated 41.27 million visits in September 2026 per Semrush). This combination points to a durable position in its niche.
Product Line Growth: The company has expanded into open-access journals, with multiple launches in 2023–2024 and ongoing development highlighted by Built In. These moves indicate growth beyond core paper sharing and continued product investment.
Investor Backing & Capital Strength: The business secured a $23 million Series D in 2022 and has attracted significant venture funding overall. Such backing supports operational stability and further development initiatives.
At Sprinter Health, we're focused on dramatically expanding access to healthcare by reimagining the patient experience—delivered at home and powered by technology for scale. We’re a boots-on-the-ground clinician network for the tele-health age, bringing routine blood draws, labs, and vitals checks into people's busy lives. We have completed over 140,000 appointments in 2025 across the US!
Sprinter Health's Top Stability & Growth Strengths
Strong Revenue Growth: A sixfold year-over-year revenue increase was reported in May 2025, indicating rapid commercial momentum. Rising visit volumes from roughly 5,000 in 2022 to 125,000+ in 2025 further reinforce this trajectory.
Market Expansion: Operations expanded from five states in 2023 to 18 by May 2025 and to nearly 25 states by February 2026. Coverage increasingly spans Medicare, Medicaid, and Marketplace populations, widening the addressable market.
Investor Backing & Capital Strength: A $55 million Series B in May 2025 brought total funding above $125 million, led by prominent investors. This capital base supports ongoing technology, staffing, and multistate rollout.
Notion is a collaborative AI workspace. Teams use it to store knowledge, run projects, take meeting notes, and build AI workflows — all in one place, so AI always has the context it needs to be useful. We're building the layer where AI stops being a chat window and starts being part of how work gets done. Knowledge, decisions, and action...
Notion's Top Stability & Growth Strengths
Strong Revenue Growth: Available reporting indicates ARR exceeded $600M by late 2025 and was estimated near $865M by mid-2026, pointing to rapid expansion of the subscription business. Company commentary notes growth acceleration in 2025 alongside higher-value plans and usage-based additions tied to AI.
Innovation-Driven Growth: Evidence suggests AI adoption is a major revenue driver, with a rising share of ARR linked to AI-enabled customers and swift uptake of new AI offerings such as agents. These capabilities appear to be prompting upgrades to premium tiers and expanding monetization beyond core workspace features.
Investor Backing & Capital Strength: An employee share tender at an $11B valuation with participation from existing and new investors indicates continued access to capital and confidence in the trajectory. Reports of cash-flow positivity further underscore financial resilience.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has accelerated, with fiscal Q2 2027 rising 30% year over year to $771.8M after fiscal 2026 grew 23% to $2.46B. Management also raised fiscal 2027 revenue guidance to about $2.99–$3.03B.
Customer Loyalty & Retention: Existing customers are expanding spend, as net revenue retention reached 122% and customers generating at least $100,000 in ARR grew to nearly 3,000. Total customers also increased to roughly 70,600, indicating broadening adoption alongside expansion within accounts.
Healthy Cash Flow: Free cash flow nearly doubled to $137.6M in Q2 FY2027, alongside an improved non-GAAP operating margin of 24% and a swing to positive GAAP net income. Reported cash and short-term investments were approximately $2.4B at quarter-end.

Adyen (ADYEN:AMS) is the financial technology platform of choice for leading companies. By providing end-to-end payments capabilities, data-driven insights, and financial products in a single global solution, Adyen helps businesses achieve their ambitions faster. With offices around the world, Adyen works with the likes of Meta, Uber, H&M, eBay, and Microsoft.
Adyen's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue has risen at double-digit rates across FY 2025 and H1 2026, alongside a similar step-up in processed volumes. Management also raised its full‑year growth outlook, indicating confidence in continued expansion.
Profitability: Earnings expanded meaningfully in 2025 with a higher EBITDA margin, and profitability continued to increase in H1 2026. While costs rose, operating profit remained at a high level.
Product Line Growth: The company is broadening beyond core processing into embedded finance, AI-enabled commerce, loyalty, and usage-based billing. Expansion of in‑store/unified commerce and platform offerings adds new revenue opportunities.
Altana powers agentic trade workflows and public-private collaboration across product value chains — the source of truth for where products come from. With Altana, businesses can prove compliance before goods ship and build more efficient, resilient, and secure supply chains. Logistics providers can automate the full brokerage workflow, and governments can promote economic security, manage borders, and enable the flow...

Altana's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Evidence highlights a $200 million Series C in July 2024 at a $1 billion valuation with participation from prominent investors, indicating substantial capacity to fund expansion. While valuation alone does not confirm revenue growth, the capital base supports continued scaling.
Market Expansion: Adoption appears to be widening across major logistics providers and governments, including an expanded CBP contract, a UK government program, FedRAMP High authorization, and reported daily use by more than 5,000 CBP agents. Partnerships such as Maersk and work with multiple governments suggest broader reach across sectors and geographies.
Product Line Growth: The July 2026 acquisition of Cervo AI extends capabilities from supply-chain intelligence into automated customs-entry workflows. Additional deployments like Product Passports and tariff tools indicate a deepening and broadening of the offering.
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose 16% in 2025 and increased 14% year over year in Q2 2026, alongside gains in gross dollar volume, cross-border volume, and switched transactions. Feedback suggests this growth spans both the core network and international activity.
Profitability: Operating income and net income grew faster than revenue in Q2 2026 (operating income +17%, net income +19%), with full-year 2025 also showing double-digit profit increases. These results indicate operating leverage and earnings expansion alongside sales growth.
Diversified Revenue Streams: Value-added services and solutions grew roughly 18%–23% in recent periods and now comprise a substantial share of total revenue, including cybersecurity, fraud prevention, authentication, and analytics. This broadens the business beyond card transactions and supports continued expansion.



