

Top Tech Companies in San Francisco Bay Area, CA (10,000+)
PagerDuty, Inc. (NYSE:PD) is a global leader in digital operations management, enabling customers to achieve operational efficiency at scale with the PagerDuty Operations Cloud. The PagerDuty Operations Cloud combines AIOps, Automation, Customer Service Operations and Incident Management with a powerful generative AI assistant to create a flexible, resilient and scalable platform to increase innovation velocity, grow revenue, reduce cost, and...

PagerDuty's Top Stability & Growth Strengths
Profitability: FY2026 marked the first full year of GAAP profitability, and Q1 FY2027 delivered a fourth consecutive GAAP‑profitable quarter. Profit guidance and expanding non‑GAAP operating margins indicate continued bottom‑line strength.
Healthy Cash Flow: Free cash flow was $102.7M in FY2026 and $41.2M in Q1 FY2027. Cash and investments of $444M and a $100M share repurchase authorization underscore liquidity to invest while returning capital.
Future-Ready Strategy: Management emphasizes AI‑first Operations Cloud offerings and a new usage‑based package aimed at re‑accelerating growth. Product and packaging moves are positioned to drive longer‑term expansion and retention.

Doximity is the leading clinical AI company with the largest network of U.S. clinicians. Doximity’s AI-powered workflow platform is trusted by over 85% of U.S. physicians and 300+ health systems. Doximity's mission is to help clinicians be more productive so they can provide better care for their patients. We are physicians-first, putting technology to work for doctors instead of the...

Doximity's Top Stability & Growth Strengths
Strong Market Position & Advantage: The platform reports a community of 3+ million members and coverage of more than 85% of U.S. physicians, reinforcing strong network effects and defensible reach. This verified penetration underpins commercial access to prescribers across its marketing, hiring, and workflow offerings.
Innovation-Driven Growth: Engagement momentum is evident with workflow active prescribers up 30%+ year over year and AI Search queries up 25%+ quarter over quarter. Management is investing in AI-driven workflow tools (e.g., Doximity Ask) to deepen usage and expand monetization.
Investor Backing & Capital Strength: The board authorized up to $500 million in additional share repurchases during FY2026, signaling balance‑sheet strength and long‑term confidence. Capital return alongside continued product investment suggests room to navigate near‑term variability.
Zeta Global (NYSE: ZETA) is the AI Marketing Cloud that leverages advanced artificial intelligence (AI) and trillions of consumer signals to make it easier for marketers to acquire, grow, and retain customers more efficiently. Through the Zeta Marketing Platform (ZMP), our vision is to make sophisticated marketing simple by unifying identity, intelligence, and omnichannel activation into a single platform –...
Zeta Global's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is accelerating with multiple raised full‑year outlooks and consecutive quarters of rapid top‑line increases. The business also highlights a long “beat and raise” cadence into 2026.
Profitability: GAAP net income turned positive in 2026 alongside expanding adjusted EBITDA. Management continues to guide to improved margins through the year.
Healthy Cash Flow: Free cash flow is rising and full‑year cash generation guidance was increased. Disclosures point to stronger operating cash flow through the first half of 2026.
Biotechnology is rewriting life as we know it, from the medicines we take, to the crops we grow, and the household goods that we rely on every day. But moving at the new speed of science requires better technology. Benchling’s mission is to unlock the power of biotechnology. The world’s most innovative biotech companies use Benchling’s R&D Cloud to power the...
Benchling's Top Stability & Growth Strengths
Innovation-Driven Growth: New AI-focused capabilities (e.g., AI Connectors built on Model Context Protocol) and a stated push to be an “AI platform for biotech R&D” signal ongoing product investment. Reported usage of Benchling AI across 500 biotech companies underscores adoption of these innovations.
Strategic Partnerships: The January 2026 collaboration with Lilly’s TuneLab is positioned to bring proprietary models to scientists across Benchling’s customer base. Acqui-hires of ReSync Bio and Sphinx Bio in 2025 were used to accelerate the AI roadmap.
Strong Revenue Growth: ARR was independently estimated around the low-$200 millions by mid-2024 with year-over-year increases, indicating continued top-line expansion. While the pace has moderated versus earlier years, the trajectory remains positive.

The database market is big. How big? Well, according to IDC, it’ll reach $153 billion by 2027. And MongoDB is at the forefront of that innovation with thousands of customers across the globe. We empower developers and businesses to build and deploy the applications they want, wherever they want.
MongoDB's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 23% in FY2026 to about $2.46B, with Q4 FY2026 up 27% year over year and Q1 FY2027 up 25% year over year. Management guided FY2027 revenue to roughly $2.92–$2.96B, indicating continued double‑digit expansion.
Healthy Cash Flow: Operating cash flow reached about $505M in FY2026, and management highlighted “rule‑of‑40” performance in Q4. Recent updates also cite strong free cash flow in Q1 FY2027.
Innovation-Driven Growth: Atlas is the primary growth engine and reached roughly 73% of FY2026 revenue (about 75% in Q1 FY2027), with Atlas revenue growing around the high‑20s to ~30% year over year in recent periods. AI‑related additions such as vector search and Automated Embeddings (via Voyage AI) are positioned as catalysts for further adoption.
.png)
The New Relic Intelligent Observability Platform helps businesses eliminate interruptions in digital experiences. New Relic is the only AI-strengthened platform to unify and pair telemetry data to provide clarity over your entire digital estate. We move your problem solving past proactive to predictive by processing the right data at the right time to maximize value and control costs. That’s why businesses...

New Relic's Top Stability & Growth Strengths
Strong Market Position & Advantage: Analyst recognitions place New Relic in the Leaders tier for observability and AIOps, and the company reports holding the No. 1 vendor share in Japan’s APM/observability market. These signals point to durable competitive standing across core categories and select geographies.
Innovation-Driven Growth: Ongoing platform and AI releases through 2025–2026 (e.g., Core Observability enhancements and new AI capabilities such as Autopilot and Ground Truth) indicate sustained product velocity. This cadence suggests active investment aimed at expanding platform adoption and wallet share.
Strategic Partnerships: Milestones and momentum through cloud marketplaces (AWS and Azure) and integrations with ecosystems like ServiceNow highlight meaningful channel reach. These partnerships serve as scalable routes to market that can complement direct sales and consumption growth.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Subscription revenue reached $3.877B in Q2 2026, growing strongly year over year, with total revenue also advancing. The company raised its full-year 2026 subscription outlook to $15.76–$15.78B and guided continued double-digit growth into Q3.
Product Line Growth: “ServiceNow AI” surpassed $1B in ACV in Q2 2026, acting as a catalyst for deal activity and upsell. Newer AI capabilities layered onto core workflows are described as adding incremental momentum.
Resilient & Sustainable Growth: Current and total RPO climbed to $13.20B and $29.0B, respectively, indicating strong contracted demand ahead. The number of customers above $5M in ACV increased meaningfully, supporting durable multi‑year expansion.
Altana powers agentic trade workflows and public-private collaboration across product value chains — the source of truth for where products come from. With Altana, businesses can prove compliance before goods ship and build more efficient, resilient, and secure supply chains. Logistics providers can automate the full brokerage workflow, and governments can promote economic security, manage borders, and enable the flow...

Altana's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A $200M Series C in July 2024 at a reported $1B valuation provides material resources for product expansion and scaling. Active hiring across engineering, product, sales, and government affairs aligns with investment-fueled growth plans.
Market Expansion: U.S. Customs and Border Protection executed a formal two-year contract to test the platform in 2025. FedRAMP High authorization in February 2026 reduces procurement friction with federal agencies and regulated customers, positioning the company for broader rollout.
Product Line Growth: The July 2026 acquisition of Cervo AI enables an end-to-end, agentic customs brokerage workflow. Altana states this brings its logistics customer base to “8 of the 10 largest logistics providers,” indicating capability-driven expansion.
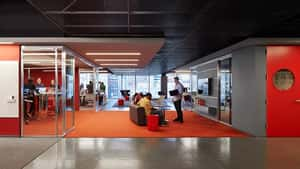
We are a global investment research and financial data company with 40-plus offices across North America, Europe, Australia, and Asia. Our products and services are used daily by individual investors, financial advisors, asset managers, retirement plan providers, and institutional investors. We provide data, research, and analysis across managed investment products, publicly listed companies, private capital markets, debt securities, and real-time...
Morningstar's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue up 9.6% year over year in Q2 2026 (6.8% organic; 8.2% excluding product sunsets), with 2025 up 7.5% and year‑to‑date 2026 up 10.2% on a reported basis. Growth is led by Morningstar Credit and core data/software platforms such as Morningstar Direct and PitchBook.
Profitability: Operating and adjusted operating margins expanded in Q2 2026 alongside a 29% rise in adjusted diluted EPS to $3.10, and 2025 saw increases in operating income and adjusted operating income. These gains were supported by stronger contribution from Credit and the accretive effect of the CRSP acquisition.
Healthy Cash Flow: Free cash flow and operating cash flow increased sharply in Q2 2026, with free cash flow nearly doubling year over year. This improved cash generation coincided with active buybacks and dividends.

Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising rapidly, with Q2 FY2026 results well above the prior year and management increasing the full‑year outlook while guiding continued momentum into Q3. These signals indicate sustained top‑line acceleration rather than a one‑off spike.
Resilient & Sustainable Growth: Contracted demand expanded, as current remaining performance obligations grew strongly in Q2 FY2026. Upmarket customer gains and elevated net retention further point to durable expansion from existing cohorts.
Innovation-Driven Growth: An AI/edge “inference layer” launch and ongoing Workers AI/Radar updates show active platform expansion and growing developer adoption. This product velocity positions the business to capture emerging AI‑driven workloads.
Wells Fargo & Company (NYSE: WFC) is a leading financial services company that has approximately $2.2 trillion in assets. We provide a diversified set of banking, investment and mortgage products and services, as well as consumer and commercial finance, through our four reportable operating segments: Consumer Banking and Lending, Commercial Banking, Corporate and Investment Banking, and Wealth & Investment Management....
Wells Fargo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with Q2 2026 up roughly 9% and broad-based increases across Consumer, Commercial, Corporate & Investment Banking, and Wealth. Management also points to continued momentum across both net interest income and fee businesses.
Profitability: Net income and EPS have increased (e.g., Q2 2026 net income around $6.4B and EPS up 25%), and full‑year 2025 earnings improved versus 2024. Efficiency gains contributed to better margins, including an improved efficiency ratio.
Cost & Operational Efficiency: Multi‑year efficiency initiatives, headcount reductions, and branch optimization have supported operating leverage and an efficiency ratio near 60%. The company emphasizes profit growth driven by productivity rather than staff expansion.
At Crunchyroll, we deliver what anime fans love—anytime, anywhere. With the world’s largest anime streaming library, we connect fans to the stories, characters, and creators they love. But Crunchyroll is more than just a destination to watch anime—it's a global ecosystem where anime lives and breathes beyond the screen. From streaming and theatrical releases to merch, games, news, events, and music, we...

Crunchyroll's Top Stability & Growth Strengths
Strong Revenue Growth: Paid subscribers increased from over 17 million to over 21 million as of March 31, 2026, and Sony cited higher revenues from Crunchyroll mainly due to paid-subscriber growth with guidance pointing to further gains. This indicates ongoing top-line momentum specifically attributed to the service within Sony’s Pictures segment.
Strong Market Position & Advantage: Crunchyroll is framed as the leading dedicated anime platform with the world’s largest anime library, broad global availability, and the consolidation of Funimation, and is positioned alongside Netflix as a dominant player in overseas anime streaming. This scale and catalog depth support acquisition and retention across many markets.
Future-Ready Strategy: Sony positions anime—and Crunchyroll specifically—as a core growth pillar, with initiatives spanning streaming, e‑commerce/merch, games, and manga plus cross‑company IP synergies. This integrated approach is intended to deepen monetization and expand fan touchpoints.
Toast is the all-in-one platform built for restaurants of all sizes. Toast provides a single platform of software as a service (SaaS) products and financial technology solutions that give restaurants everything they need to run their business, including point of sale, payments, supplier management, digital ordering and delivery, marketing and loyalty, and team management. By serving as the restaurant operating...
Toast's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose about 23% year over year in Q2 2026 and 24% for full-year 2025, with ARR up 25% and GPV up 22% reinforcing a scaling top line. Guidance for 2026 recurring gross profit growth of roughly 23–25% further underpins momentum.
Profitability: Operating income and EPS roughly doubled year over year in Q2 2026 (operating income $152M vs. $80M; diluted EPS $0.26 vs. $0.13). Management also highlighted rising adjusted EBITDA and improved net income alongside recurring gross profit expansion.
Market Expansion: New offerings (e.g., Toast Drive‑Thru) and enterprise wins/expansions (e.g., Best Western, TGI Fridays UK, multi‑unit brands like Caribou Coffee and Potbelly) support broader adoption. The footprint reached about 180,000 total locations as of June 30, 2026, up roughly 22% year over year.
Superhuman (formerly Grammarly) is the AI productivity platform on a mission to unlock the superhuman potential in everyone. The Superhuman suite of apps and agents brings AI wherever people work, integrating with over 1 million applications and websites. The company’s products include Grammarly’s writing assistance, Docs’ connected surface for teams, Mail’s inbox management, and Go, the proactive AI assistant that...
Superhuman's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is estimated to have risen from about $30M at end‑2024 to roughly $35M by June 2025, signaling steady topline momentum prior to the acquisition. This trajectory indicates continued demand for the product heading into suite integration.
Market Expansion: Deeper Outlook compatibility and broader platform coverage (including Android) opened access to the larger Microsoft 365 user base, enabling seat expansion in businesses. Ongoing improvements to Outlook support and cross‑platform parity are positioned to reduce churn and strengthen word‑of‑mouth.
Strategic Partnerships: The July 2025 acquisition by Grammarly and the October 2025 rebrand to “Superhuman” place the email client inside a larger suite, creating cross‑sell and enterprise channel advantages. This strategic backing can accelerate adoption across organizations already using the parent company’s tools.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is described as rising from over $300M in 2025 to over $400M by mid-2026, alongside large-scale telemetry usage that signals expanding adoption. This trajectory indicates sustained top-line expansion through 2026.
Innovation-Driven Growth: AI-led capabilities such as Edwin AI are portrayed as a meaningful driver of bookings with rapid recurring revenue momentum, and the company is advancing an “Autonomous IT” roadmap. Continued AI feature launches through 2026 point to product-led expansion.
Investor Backing & Capital Strength: An $800M financing in late 2024 at around a multi‑billion valuation provides resources to accelerate platform expansion, acquisitions, and entry into new markets. This capital base supports ongoing scaling initiatives.
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding with consecutive year-over-year increases in the first half of 2026 and management raising the full‑year outlook. The quarter ended June 30, 2026 also closed at nearly a $1.5 billion annualized run rate.
Profitability: Margins and cash generation are improving, with recent quarters showing positive non‑GAAP operating income and strong free cash flow. Materials also highlight operating discipline alongside growth.
Market Expansion: International revenue is outpacing the Americas, supported by new regional hubs such as Dublin and Singapore. Rising adoption of additional channels (e.g., SMS/WhatsApp) and larger‑account wins indicate a broader addressable market.
Founded in 2020 by George Sivulka and backed by Peter Thiel and Andreessen Horowitz, Hebbia powers investment decisions for BlackRock, KKR, Carlyle, Centerview, and 40% of the world’s largest asset managers. Our flagship product, Matrix, delivers industry-leading accuracy, speed, and transparency in AI-driven analysis. It is trusted to help manage over $15 trillion in assets globally. We deliver the intelligence that...

Hebbia's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A large Series B of about $130M at roughly a $700M valuation in mid-2024 and an additional 2026 venture event signal strong access to capital and confidence from prominent investors. This financing base supports continued product and go-to-market expansion.
Strong Revenue Growth: Revenue was reported at roughly $13M and profitable by mid-2024 with claims of ~15x growth over the prior 18 months. Subsequent disclosures of 373% year-over-year growth in EMEA from FY25 to FY26 indicate continued momentum.
Market Expansion: Named deployments and expansions in finance and legal, including firm-wide or expanded use at Ropes & Gray and Seyfarth Shaw, point to deepening penetration in high-value niches. Alignment with advanced reasoning models and ongoing platform upgrades further support scaling into production use cases.
Motive builds technology to improve the safety, productivity, and profitability of businesses that power the physical economy. The Motive Automated Operations Platform combines IoT hardware with AI-powered applications to automate vehicle and equipment tracking, driver safety, compliance, maintenance, spend management, and more. Motive serves more than 120,000 businesses, across a wide range of industries including trucking and logistics, construction, oil...
Motive's Top Stability & Growth Strengths
Strong Revenue Growth: ARR rose from $338M (2023) to $417M (2024) and reached $501M by September 30, 2025, alongside revenue growth of 19% in 2024 and 22% for the first nine months of 2025. Growth in large customers—from 234 (2023) to 349 (2024) and 494 by September 2025—supports continued scale.
Investor Backing & Capital Strength: The company secured $150M in July 2025 to accelerate AI development and international expansion. This capital underpinned new product launches (e.g., Motive Analytics) and broader go‑to‑market efforts.
Customer Loyalty & Retention: Enterprise net revenue retention was cited above 127%–130%, and ARR from customers spending over $100K more than doubled since 2024. Multi‑product penetration also deepened, with 89% of Core Customers using at least two products and 40% using three or more by September 30, 2025.

Taskrabbit is a marketplace platform that conveniently connects people with Taskers to handle everyday home to-do’s, such as furniture assembly, handy work, moving help, and much more. Acquired by IKEA Group - the world’s largest furniture retailer - in 2017 At Taskrabbit, we want to make your neighborhood a little more familiar. Whether it’s a handyman (or woman!), a housecleaner, moving...

Taskrabbit's Top Stability & Growth Strengths
Market Expansion: Nationwide availability in the U.S., ongoing city-level rollouts, and operations across eight countries indicate a widening footprint. Recent announcements highlight additional service areas and partner activations through 2025–2026, pointing to sustained reach expansion.
Product Line Growth: The acquisition of Dolly and its July 2026 rebrand to Taskrabbit Delivery extend capabilities into big‑and‑bulky moving and retail logistics. Additions like Taskrabbit for Business, partner pages, and embedded checkout experiences broaden offerings beyond core household tasks.
Strong Revenue Growth: Leadership communications describe substantial multi‑year revenue increases, supported by earlier strong year‑over‑year gains. Reported momentum in moving‑related bookings and seasonal task surges in select metros reinforces underlying demand growth.
Monte Carlo is the agent trust platform that unifies data and agent observability to monitor, troubleshoot, and improve production AI systems. As enterprises prepare to deploy thousands of agents across business-critical use cases, Monte Carlo provides the reliability infrastructure to support them along this AI transformation, from human-guided agents to fully autonomous operations. Founded 2019. Backed by leading investors. Trusted...

Monte Carlo's Top Stability & Growth Strengths
Strong Market Position & Advantage: G2 has ranked Monte Carlo the #1 Data Observability platform for multiple consecutive quarters, and the company highlights enterprise wins such as Dell, American Airlines, Live Nation, and DraftKings. These signals point to prominent positioning in its category through 2025–2026.
Innovation-Driven Growth: Recent launches expand the platform from data observability into data + AI/agent trust, including Agent Observability, an Operations Agent, and unstructured data monitoring. New integrations and an EU hosting option broaden use cases and geographic reach.
Investor Backing & Capital Strength: A substantial Series D in 2022 at around a $1.6B valuation provides runway to invest through recent years. This capital base underpins expansion in product and go‑to‑market alongside visible enterprise traction.



